

Piggy Bank Allowance - Bomad
Reviews 4.4Category ParentingDownloads50.00K
Screenshots
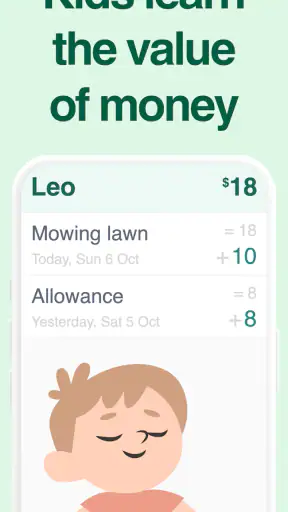
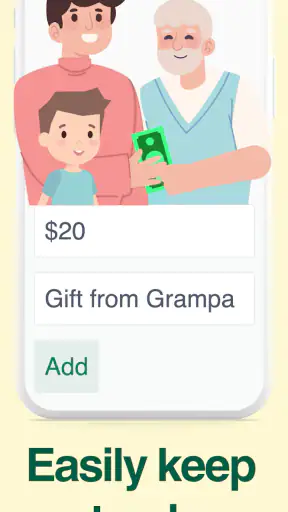
Download
Download OnGoogle PlayDownload OnApp StoreDownload theAPK FilePros
- Simple way to track children’s allowances and savings goals.
- Encourages kids to learn budgeting through regular money management.
- Useful for recording chores
- rewards
- and deductions in one place.
- Digital tracking reduces the need for cash or paper allowance charts.
- Can help parents discuss spending habits and financial responsibility.
Cons
- May require consistent parent input to keep balances and chores accurate.
- Features may feel limited for families needing detailed budgeting tools.
- Children without their own device may have limited access to the app.
- Allowance tracking may not support every family’s preferred currency or system.
- Some users may prefer a shared family wallet over separate child accounts.
 Review of Piggy Bank Allowance - Bomad by Appcracy
Allowance apps often promise to make pocket money easier, but the useful test is much more practical: can a child understand what happened to their money, and can a parent keep the routine simple enough to maintain? After spending time with Piggy Bank Allowance - Bomad, I found that its strongest idea is the use of separate saving and spending jars or pots. That single visual choice gives ordinary allowance conversations a clearer shape than a notebook, a family chat, or loose coins on a shelf.
This is a free parenting app from Graeme P, aimed at families who want to track children’s allowance and introduce basic money habits. It is rated for Everyone and supports devices running Android 9 or later. The app has reached more than 50,000 installs and holds a 4.4 average from around 685 ratings, which suggests that its straightforward approach has found a useful audience. Optional in-app purchases range from $1.99 to $29.99 per item, so I would still check the purchase screen carefully before handing the phone to a child.
Why the jar-and-pot idea matters
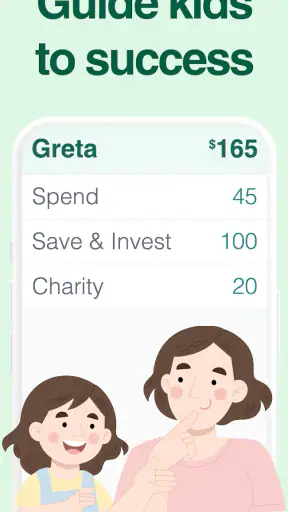
The central capability is not merely recording that a child received money. It is separating money by purpose. A spending pot can represent money available for a small treat, while a saving pot can hold money for something that matters later. In my experience, that distinction is much easier for a young child to grasp than a single balance that rises and falls without explanation.
That matters because allowance is usually less about accounting and more about forming a repeatable habit. When all the money sits in one total, a child may hear “you have enough” without understanding whether spending now affects a larger goal. Separate pots turn the conversation into something concrete: this part is available, and this part is being kept aside.
I see the app’s value most clearly when a parent uses it as a shared conversation tool rather than as a silent ledger. The parent can record an allowance, decide how it should be divided, and then talk through the result with the child. The screen becomes a prompt for questions such as, “What are you saving for?” or “Would you rather spend this portion today?” Those questions are more educational than simply announcing a balance.
The most useful feature is the visual separation of short-term spending from longer-term saving. It gives children a basic model of budgeting without requiring them to understand bank accounts, interest, cards, or complicated financial language. For early money lessons, that restraint is a strength.
How I would set up a family routine
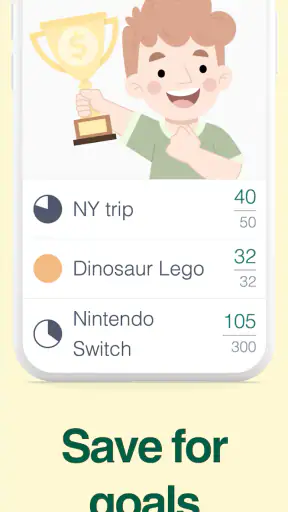
I would begin by agreeing on what the pots mean before entering any amounts. The spending pot should have a clear rule, such as money the child may choose to use, while the saving pot should have a purpose that the child can name. A vague saving balance is easy to ignore; a balance connected to a desired item, outing, or personal target is easier to revisit.
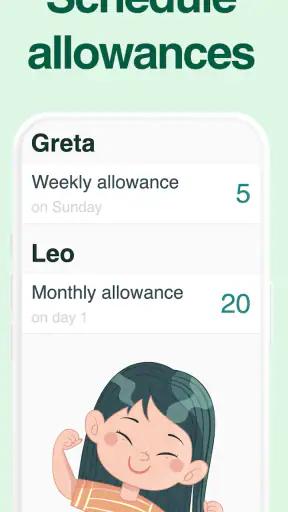
The next step is consistency. Whether allowance is given weekly, tied to chores, or handled informally, the parent should update the app at the same moment each time. Doing it during a regular family routine is better than waiting until someone remembers. The app can track the result, but it cannot create the routine by itself.
I also recommend letting the child look at the pots while the update is made. That small action changes the app from a parent-only record into a shared learning exercise. A child can see that adding money to saving means less is immediately available for spending, and that choosing to spend has a visible consequence. The trade-off becomes understandable without a lecture.
One practical tip is to avoid changing the rules every time a child asks for something. If the saving pot is repeatedly emptied to cover an impulse purchase, the separation loses its teaching value. It is better to agree in advance which pot can be used for what, then make exceptions openly rather than quietly altering the record.
What using it feels like day to day
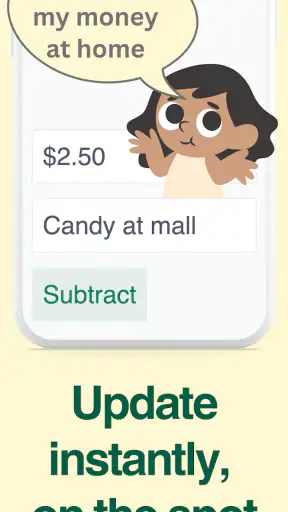
In everyday use, this kind of tracker works best when updates are brief. A parent does not need to turn every allowance into a financial lesson. A quick entry followed by a short check of the pots is enough for most days. The app’s role is to keep the agreed arrangement visible, not to add paperwork to family life.
Imagine a child receives their regular pocket money on a weekend morning. Instead of handing over everything at once, the parent opens the tracker and divides the amount between spending and saving. Later that week, the child wants a small toy. The spending pot provides a natural answer: the child can see whether the choice fits within the money available, while the saving pot remains protected for the larger goal. If the child chooses to wait, that decision is visible too.
That scenario shows an important strength: the app makes delayed gratification easier to discuss. A paper chart can do something similar, but a digital pot is quicker to update and easier to check when the question comes up unexpectedly. The child does not have to remember a handwritten total, and the parent does not have to reconstruct several past changes from memory.
Another useful workflow is to review the pots before a planned purchase rather than at the moment of asking. If a child is saving for something specific, checking progress ahead of time can turn the purchase into a decision with context. The child may discover that they are close to the goal, or decide that a smaller spending choice is worth making. This is more meaningful than treating the app as a simple “yes” or “no” machine.
Parents should also be clear about whether the app represents real cash, a promise of future money, or a mixture of both. If the child sees a digital spending balance but the parent has not actually set that money aside, confusion can follow. I would use the tracker as an agreed record and explain what the displayed amount means in your household. The clearer that agreement is, the more useful the pots become.
A realistic best-case scenario
The strongest use case is a family with one or more children who are beginning to make independent choices but still need a simple framework. The parent wants to encourage saving without turning allowance into a formal financial system. In that situation, the jars provide just enough structure: one place for money that can be used soon and another for money that should stay untouched.
For example, a child may want to save toward a larger purchase while still having permission to spend small amounts. A single balance forces an all-or-nothing decision. Separate pots allow both priorities to exist at once. The child can enjoy some freedom without losing sight of the longer goal, and the parent can discuss choices without taking over every decision.
This can also help when siblings have different goals. One child may be saving, while another is more interested in spending. A shared family explanation of the pots keeps the rules understandable without requiring identical behavior. The point is not that every child must divide money in the same way; it is that each child can see the consequence of their own arrangement.
I would be especially comfortable recommending it for families trying to move away from repeated “Can I have it?” conversations. The app does not eliminate those questions, but it gives them a visible reference point. Instead of negotiating from memory, parent and child can look at the agreed spending amount and decide within that boundary.
There is also value in using it during a reset. If a child has never tracked allowance before, start with a modest rule and keep it stable for a few cycles. Do not attempt to record every historical coin or recreate years of spending. The educational benefit comes from a clear starting point and repeated choices, not from perfect financial archaeology.
Where the simplicity creates trade-offs
The same simplicity that makes the app approachable may feel limiting to families looking for a complete household finance platform. I would not choose it as a replacement for a bank account, a card-management service, or a detailed chore-and-reward system. Its appeal is the focused allowance record with saving and spending pots, not a broad collection of financial tools.
It also depends heavily on parental follow-through. If allowance changes are forgotten, entered late, or handled differently from the rules discussed with the child, the displayed pots stop reflecting reality. No tracker can solve an inconsistent agreement. Parents who want a fully automatic system may find manual upkeep frustrating, particularly in a busy household.
Another trade-off is that a digital balance can make money feel abstract. Physical coins have a sensory quality that helps some children understand quantity. Piggy Bank Allowance can support the lesson, but I would sometimes combine it with real-world practice: let the child count cash, compare prices, or decide how much to keep after a purchase. The app is strongest as the organizing layer, not as the entire lesson.
Families should also think about privacy and device habits in a practical way. Because this is a child-focused money tracker, I would avoid treating the phone as a toy that the child can use without supervision if purchases are available inside the app. The Everyone age rating makes it broadly suitable from a content perspective, but age suitability does not remove the need for a parent to control spending and explain what the figures represent.
The current version is 2.0.266, and the minimum operating system is Android 9. That makes the app accessible to many Android users, although anyone using an older device should check compatibility before planning a family routine around it. The app is free to start, but the presence of optional purchases means “free” should be understood as an entry point rather than a guarantee that every possible option costs nothing.
Compared with a spreadsheet, the jar concept is friendlier for a child and less dependent on formulas. Compared with a paper chart, it is easier to update privately and check when away from home. Compared with a general chore app, it keeps the money lesson in focus instead of making allowance one item among many household tasks. Those are meaningful advantages, but a spreadsheet may suit an older child who wants detailed records, and a physical chart may be better for a child who learns through writing and handling coins.
Who will gain the most from it
I think the best audience is parents of children who are ready to practice choosing, waiting, and saving but do not need a complicated interface. It is also a good fit for adults who want a visible way to divide allowance without opening a real financial account for a child. The separate pots create a gentle middle ground between giving unrestricted cash and controlling every purchase.
It can be particularly helpful when a child struggles to hold a long-term goal in mind. Seeing a saving pot grow makes progress easier to notice. A parent can use that progress to encourage patience, while still leaving room for the child to make mistakes with the spending portion. That balance—protected saving alongside limited freedom—is where I see the app making the biggest difference.
I would be more cautious about recommending it to teenagers who already expect card payments, transaction histories, detailed categories, or direct control over their own accounts. They may quickly outgrow the jar metaphor. Likewise, families that want chores to trigger complex rewards should look for a tool designed around task management rather than adapting this focused allowance tracker beyond its natural purpose.
Before installing, I would answer three questions as a family. What does each pot mean? When will the record be updated? Which decisions belong to the child? If those answers are clear, the app has a fair chance of becoming useful. If the family has not agreed on the rules, the screen may simply make disagreements more visible.
My recommendation after using the approach
Piggy Bank Allowance - Bomad succeeds because it does not try to make children learn adult banking all at once. Its saving and spending pots offer a simple visual language for two competing priorities, and that language can improve allowance conversations in a way that a bare total often cannot. I especially like it as a shared parent-and-child routine, where the numbers support a decision instead of replacing one.
My recommendation is strongest for younger users and families starting their first structured allowance habit. Keep the rules simple, update the pots consistently, and connect saving to a real goal. Use real coins or prices alongside the app when a child needs a more physical understanding of money, and supervise any optional purchases rather than assuming the free download is the whole experience.
For families wanting a lightweight, free starting point in the parenting category, Piggy Bank Allowance - Bomad is a sensible choice. It will not automate responsibility, and it is not a full financial-management system. What it does offer is more focused and, in the right household, more valuable: a clear place to show that spending today and saving for later are different choices.
FAQ
What is Piggy Bank Allowance - Bomad and who is it designed for?
Piggy Bank Allowance - Bomad is a family-focused allowance management app designed to help parents organize children’s pocket money, chores, savings, and spending goals. It provides a digital way to record allowances and encourage better money habits. The app is mainly useful for families who want a clearer alternative to tracking cash payments manually or using paper charts.
Can parents use the app to manage chores and connect them with allowances?
Yes, the app is intended to help parents organize household tasks and associate completed chores with allowance payments or rewards. Parents can usually define responsibilities, monitor progress, and keep a record of what has been earned. Before downloading, families should review the available task and reward options to confirm that they match their preferred allowance system and children’s ages.
Does Piggy Bank Allowance - Bomad handle real money or actual payments?
The app primarily functions as a digital allowance and money-management tracker, so users should not automatically assume that it replaces a bank account, debit card, or payment service. Depending on the version and platform, some features may only record balances, earnings, savings, or spending. Parents should check the current app description and permissions to understand whether any banking or payment integrations are supported.
Is Piggy Bank Allowance - Bomad suitable for teaching children about saving and budgeting?
It can be useful as an educational tool because children can see how money is earned, divided, saved, or spent instead of treating allowances as invisible transactions. Parents can use the records and goals to discuss budgeting, delayed gratification, and responsible spending. However, the app works best alongside regular conversations, since a digital balance alone cannot replace practical financial guidance.
Is the app safe for children, and what should parents check before installing it?
Parents should review the app’s privacy policy, age rating, permissions, advertising practices, and any in-app purchases before allowing a child to use it. It is also important to determine whether children need their own accounts or can access the app through a parent-controlled profile. Because features and privacy terms may change, checking the latest information on the official Google Play or App Store listing is recommended.


