

DANA Indonesia Digital Wallet
Reviews 4.6Category FinanceDownloads100.00M
Screenshots
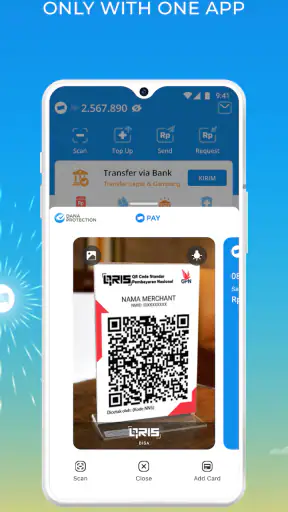
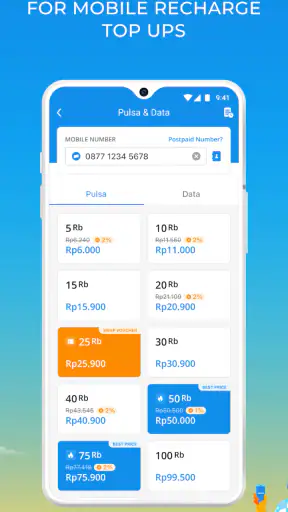

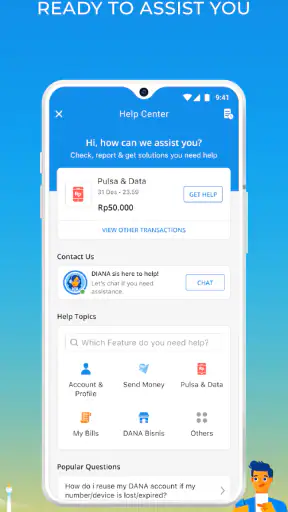
Download
Download OnGoogle PlayDownload OnApp StoreDownload theAPK FilePros
- User-friendly interface for easy navigation.
- Quick and secure transactions anytime.
- Supports a wide range of payment options.
- Offers cashback and rewards for users.
- 24/7 customer support available.
Cons
- Limited to Indonesian users only.
- Requires stable internet connection.
- Occasional app lag during peak hours.
- Some features require verification.
- Not all merchants accept DANA payments.
 Analysis by Appcracy
When I judge a digital wallet, I care less about a long list of possible tasks than about whether it earns a place in my everyday routine: can I reach it quickly, understand what I’m about to pay, and keep track of money moving in and out? DANA is an Indonesian finance app from PT Espay Debit Indonesia Koe, and its appeal is easy to grasp: it puts cashless payments and wallet-based transactions in one place. It is free to install, rated for Everyone, and has grown into a familiar option, with over 100 million installs and an average rating of 4.6 from around 9 million ratings. Those figures tell me it has broad reach, but the more useful question is whether its day-to-day approach suits you.
What the current version tells me
The app’s current version is 2.106.0, following its release on May 7, 2019. That gives a simple, verifiable sense of its history: DANA is an established product that has continued to receive version changes, rather than a newly launched wallet. I wouldn’t treat a version number alone as proof that every part of the experience has improved, though. What matters to an existing user is whether the app stays understandable and dependable as it changes. My practical advice is to read update notes before installing a new release and check that your usual payment route still appears where you expect it.
Where a wallet can make a real difference
The strongest case for DANA is routine spending, not replacing every financial service you use. Imagine meeting a friend after work: you pay at a participating merchant, then send your share for dinner without digging for cash or switching between a payment tool and a separate money-transfer app. That is the sort of small convenience that can make a wallet worthwhile. I’d also consider it for someone who wants to keep everyday digital payments separate from a bank account’s main interface. But convenience depends on the places and people you actually pay; if your regular merchants or contacts don’t use compatible payment routes, the wallet may become one more app to maintain.
Guides and Stories About DANA Indonesia Digital Wallet
Changes, habits, and sensible limits
For people who already use DANA, continued versions can mean the interface and routine evolve over time. I’d make a habit of checking the recipient, amount, and any displayed fee or confirmation details before approving a transfer, especially after an update changes where buttons sit. A digital wallet can make payment faster, but speed is not the same as certainty: pause at the final confirmation screen rather than tapping through automatically. Keep your phone’s own screen lock in place, use the app’s available sign-in protections, and avoid making transactions on a device you do not control. These are modest habits, but they matter more than assuming that an app alone can prevent every mistake.
Compared with carrying cash, a wallet is more convenient for supported cashless payments, while cash remains useful when a merchant does not accept digital payment or your phone is unavailable. Compared with a bank app, DANA is centered on wallet-style transactions rather than being the place I would expect to manage every banking need. Compared with using several single-purpose payment apps, one wallet can reduce app-hopping, although only if it covers the transactions you actually make. I would not choose it as my only financial tool without first checking how it fits my own payment habits and keeping another way to pay for essential purchases.
My bottom line is that DANA makes the most sense for someone in Indonesia who regularly pays digitally and wants a dedicated wallet for everyday transactions. It is less compelling if you rarely use cashless payments, prefer to keep all money activity within a bank’s own app, or do not want to manage another account and its security settings. Before relying on it, I’d check the current payment options in the app, understand the confirmation steps, and keep a backup payment method for moments when a phone or connection is not available. That is a more useful test than judging a wallet by popularity alone.
A Convenient Way to Pay
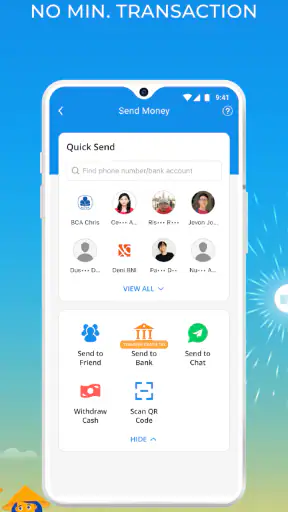
First off, let me just say that setting up DANA was a breeze. Within minutes, I was up and running, ready to make my first transaction. It’s designed with user-friendliness in mind, which is perfect whether you’re tech-savvy or a novice in the digital space. From paying bills to transferring money to friends and family, DANA does it all with a few taps. I especially appreciated the seamless integration with various merchants, making everyday transactions more straightforward than ever.
Worth a Read Next
How Uber's Driver App is Transforming the Gig Economy
Mastering Microsoft SwiftKey: Unleash the AI Keyboard's Hidden Powers
Galaxy Attack: The Arcade Shooter Taking Over Mobile
Why Bitmoji Stands Out as This Week's Top App
How Instagram Dominates the Digital Ecosystem
How X is Transforming Social Media Dynamics
Security Features That Matter
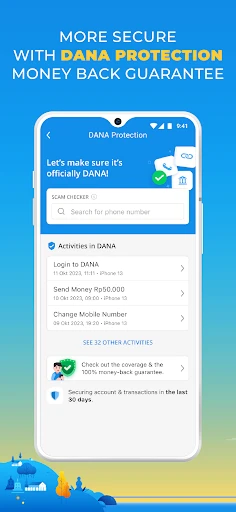
Now, I know what you’re thinking—how secure is this app? Well, DANA has put a lot of thought into security features. It uses encryption, and there are multiple layers of authentication to ensure your money is safe. These include PINs, fingerprint scanning, and facial recognition. Knowing that my transactions and data are secure gives me peace of mind, which is crucial in today’s digital age.
Rewards and Promotions
Who doesn’t love a good deal? With DANA, you’re often greeted with a slew of promotions and rewards. Whether it’s a cashback offer or discounts at your favorite stores, there’s always something to keep an eye out for. This not only adds value to the app but also makes spending a tad more rewarding. I found myself eagerly checking the promotions section to see what’s new and exciting.
User Experience and Interface
The user interface is sleek and modern, with a clean design that makes navigation a breeze. Everything is laid out intuitively, which means you spend less time figuring things out and more time enjoying the benefits. The app is responsive, and transactions are processed swiftly, which is fantastic when you're in a rush.
In conclusion, DANA is not just another digital wallet; it’s a comprehensive financial tool that simplifies your life. With its ease of use, robust security, and tempting promotions, it’s hard not to recommend it. Whether you’re looking to pay a bill, send money to a friend, or simply enjoy the convenience of digital transactions, DANA has got you covered. Give it a try—you might just find it becoming an indispensable part of your daily routine.
Making it fit your routine
A useful way to decide whether DANA belongs on your phone is to track the payments you already make for a few ordinary days. Notice which ones involve cash, which ones happen through a bank app, and which require asking someone else to pay first. If the same kinds of transactions keep coming up and DANA supports them in your situation, putting that wallet balance toward those expenses may save small bits of time. If your payments are scattered across unrelated services, the benefit may be smaller than the convenience of keeping your existing routine.
I’d also treat a wallet as a tool for planned spending rather than an invitation to spend more. Before adding money or approving a payment, decide what the balance is for: a particular bill, a shared meal, or regular small purchases. That simple boundary makes it easier to notice when a promotional offer is genuinely useful and when it is merely nudging you toward an unnecessary purchase. A discount only helps if you would have made the purchase anyway and the terms suit your needs.
Small checks that prevent avoidable trouble
For transfers, I would verify the recipient’s displayed identity and the amount before confirming, especially when sending money to someone for the first time. For a merchant payment, I’d check the total on the payment screen against the amount I expect to pay. These checks sound obvious, but wallet payments can feel so quick that it is easy to skip them. If a transaction looks unfamiliar, I would stop and review it rather than repeating the payment immediately; a second tap can create confusion if the first attempt is still processing.
It is also worth thinking through what happens when your phone is low on battery or you have no reliable connection. A digital wallet cannot help much if you cannot open it at the moment you need to pay. I’d keep a modest backup option for essential purchases and avoid treating a wallet balance as the only money available to me. That is not a criticism unique to DANA; it is a practical trade-off of putting payment access on a phone.
Promotions need a quick reality check
The offers section can be useful when you are already planning to shop, but I wouldn’t browse it as a reason to spend. I look for the conditions that affect the real value: which merchant or transaction qualifies, whether there is a minimum purchase, and when an offer ends. Those details can change, so I would read the terms shown in the app before counting on a saving. If the conditions make the purchase more expensive or inconvenient than paying normally, I’d ignore the promotion and move on.
This is also where a wallet differs from a simple payment card. A card can be a familiar, direct way to pay, while a wallet may put offers and digital transfers closer to the payment flow. That can be handy, but it also asks me to pay attention to a second layer of choices. I find the wallet most useful when I know what I want to do before opening it, rather than letting banners or offers decide what I buy.
Choosing the right place for support and control
One question people often have is whether a wallet can replace their bank app. I would not assume that. DANA is best considered as a payment and transfer option within a wider financial setup, while a bank app remains the more natural place for account management and banking tasks. Keeping both can be sensible: use the wallet when its payment route is convenient, and use the bank’s own tools when you need bank-specific information or services. The right division depends on your habits, not on trying to make one app do everything.
Another practical question is how to handle an incorrect payment or a transfer that does not appear as expected. I would first check the transaction history and any status shown in the app, then compare the recipient and amount with what I intended. Keep the relevant details available before seeking help through the app’s current support options. I would avoid sending the same amount again until I understand the first transaction’s status; that small pause can prevent a delayed payment from turning into a duplicate.
People also ask whether a wallet is suitable for someone new to digital payments. In my view, the simple interface can make the first steps approachable, but a beginner should still take time to understand how payments are confirmed and how to protect access to the phone. Start with a familiar, low-stakes transaction, read each screen, and learn where the history and payment details are shown before using it for anything time-sensitive. Confidence should come from understanding the process, not from tapping quickly.
What I would watch as it keeps evolving
With an established app that continues to receive versions, I would watch for changes that affect the everyday basics: whether common payment actions remain easy to find, whether transaction records are clear, and whether the app explains each step before money moves. New options are only valuable if they make a real task simpler without making the interface harder to follow. The release history gives a reason to expect ongoing changes, but it does not by itself tell me what a future version will add or how it will perform on every device.
For existing users, my recommendation is to keep the parts of the routine that work, but give meaningful updates a quick review rather than assuming nothing has moved. For people considering a first install, I’d decide based on the local merchants and contacts they need to pay, the comfort they have with a wallet balance, and whether they are happy to manage another app securely. Those are more useful criteria than chasing every new feature. If DANA matches those needs, it can be a convenient everyday companion; if not, cash, a bank app, or another familiar payment method may be the better fit.
DANA Indonesia Digital Wallet FAQ
What is DANA and how does it work?
DANA is a digital wallet platform in Indonesia that allows users to make cashless and cardless transactions effortlessly. It works by linking your bank account or credit card to the app, enabling you to pay for goods and services, transfer money, and even pay bills directly from your smartphone. The app ensures secure transactions through multiple layers of security, including PIN codes and biometric verification.
Is DANA safe to use for online transactions?
Yes, DANA is designed with robust security features to protect users' information and transactions. It employs encryption technology, secure PIN codes, and biometric authentication to ensure that all transactions are safe and secure. Additionally, DANA is regulated by Bank Indonesia, providing an extra layer of trust and reliability for users.
Can I use DANA without an internet connection?
No, you cannot use DANA without an internet connection. The app requires a stable internet connection to perform transactions, update your account balance, and access various features. However, once a transaction is processed, you will receive a confirmation notification, which can be accessed later even if you are offline.
What are the fees associated with using DANA?
DANA offers many transactions free of charge, such as paying bills, transferring money to other DANA users, and making purchases at partnered merchants. However, there might be fees for certain services like withdrawing money to a bank account or transferring funds to non-DANA users. It's advisable to check the latest fee structure within the app or on the official website to stay informed.
How can I top up my DANA wallet?
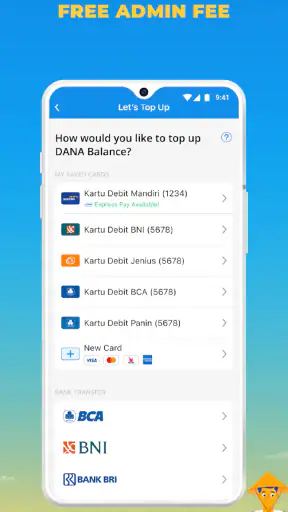
Topping up your DANA wallet is simple and can be done through various methods. You can add funds via bank transfer, through ATMs, or by using online banking services linked to your DANA account. The app also supports top-ups through convenience stores and partner merchants, providing flexibility and convenience to users seeking to maintain their wallet balance.
DANA Indonesia Digital Wallet
FinanceRead This Review in Other Languages
DANA Indonesia Digital Wallet JADANA Indonesia Digital Wallet KODANA Indonesia Digital Wallet DEDANA Indonesia Digital Wallet FRDANA Indonesia Digital Wallet PTDANA Indonesia Digital Wallet ESDANA Indonesia Digital Wallet ITDANA Indonesia Digital Wallet THDANA Indonesia Digital Wallet ARDANA Indonesia Digital Wallet HIDANA Indonesia Digital Wallet NL


