

Venmo
Reviews 4.1Category FinanceDownloads50.00M
Screenshots
Download
Download OnGoogle PlayDownload OnApp StoreDownload theAPK FilePros
- User-friendly interface
- Instant money transfers
- Social feed for transactions
- Supports credit/debit cards
- Strong security features
Cons
- Transaction fees for credit cards
- Limited international use
- Possible privacy concerns
- Must link a bank account
- Social feed may feel intrusive
 Analysis by Appcracy
I find person-to-person payment apps most useful when they remove the little bits of friction around shared costs: remembering who paid, working out the split, and asking someone to settle up. Venmo is built for that kind of everyday exchange, with a social layer that makes payments feel less formal. That can be charming among friends, though it is not automatically the best fit for every payment or every person.
Quick payments, with a social extra
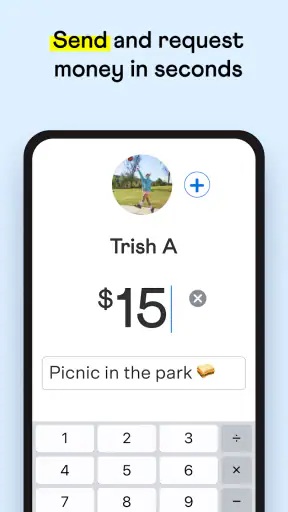
Venmo is a finance app from Venmo, and its appeal is easy to understand: it gives friends a straightforward place to send and request money. The payment note can add a joke or a reminder about what the money covered, which helps a transaction feel connected to the occasion. In my view, that small social touch is useful when everyone involved likes it, but it should never distract from checking the amount and recipient before sending.
The app has been available since May 17, 2010, and it has grown into a familiar option for people who regularly settle shared expenses digitally. It is free to download, rated for Everyone, and currently at version 10.78.1. Its average rating is 4.1 from around 871,000 ratings, while more than 50 million installs suggest that many people have tried it. Those figures show its reach, but they do not tell you whether its social style suits your own habits.
What happens during an ordinary payment
A simple way to use Venmo is to request a specific amount after a shared purchase and add a short note that makes the reason clear. If I covered lunch for a friend, for example, a note such as “lunch” is more useful later than a string of inside jokes. Keeping descriptions recognizable also makes it easier for both people to make sense of their activity when they review it.
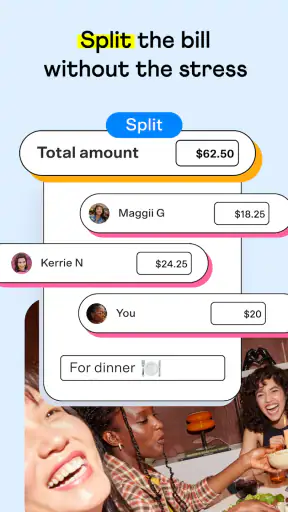
For a group bill, I would agree on the split before sending requests. That avoids the familiar confusion of one person assuming the total includes a tip while another calculates only the food. Venmo can make settling up less awkward, but it cannot decide what a fair split is; a quick conversation still matters, especially when people ordered very different things.
Privacy needs an active choice
The social feed is the feature that most clearly separates Venmo from a plain transfer tool, and it is also the part I would approach most thoughtfully. A payment note can reveal more than the amount: it might hint at where you went, who you were with, or what you bought. I would keep notes practical and check the audience setting for each payment instead of assuming that every transaction should be shared.
That habit is worthwhile even if your friends use playful notes. A joke that seems harmless in the moment can look different outside its original context. If you prefer money transfers to stay between the people involved, privacy choices matter more than the social feed’s entertainment value. The app is more comfortable when you treat sharing as optional rather than as the default way to use a payment service.
Worth a Read Next
How Uber's Driver App is Transforming the Gig Economy
Mastering Microsoft SwiftKey: Unleash the AI Keyboard's Hidden Powers
Galaxy Attack: The Arcade Shooter Taking Over Mobile
Why Bitmoji Stands Out as This Week's Top App
How Instagram Dominates the Digital Ecosystem
How X is Transforming Social Media Dynamics
Choosing how to fund and move money
Before paying, I would check which funding method is selected. The original article describes payments from a bank balance or debit card as having no fee and notes a 3% charge for credit-card payments. That makes a credit card a decision to weigh rather than an automatic choice: any rewards would need to be worth the added cost to you. Fees and transfer conditions can change, so it is sensible to review the in-app details before confirming a transaction.
There is also a difference between having money in an app balance and having it in your bank account. The original article describes a standard transfer as usually taking one to three business days, with an instant option available for a fee. I would not rely on an instant transfer as a free shortcut, and I would plan ahead if I needed the money by a particular time. When timing matters, confirm the transfer option and any charge before proceeding.
Where it fits—and where it does not
Venmo is at its best when the other person already uses it and the payment is a casual shared expense: dinner, a household purchase, or a small favor. Compared with asking everyone to bring cash, it can reduce the need to find exact change. Compared with a bank transfer, its social notes may make informal payments feel more conversational. But if your priority is a strictly private, no-frills transfer, a bank’s own payment service or another simple transfer app may feel more appropriate.
It is also worth separating person-to-person convenience from budgeting. A clear note can help explain a payment, but it does not replace a deliberate system for tracking shared rent, bills, or household contributions. Roommates might use Venmo to settle individual amounts while keeping a separate record of what is due each month. That extra record is useful when several payments happen at different times and no one wants to reconstruct the total from memory.
Small habits that prevent avoidable trouble
For recurring costs, I would settle the amount and schedule with the other person first, then make each request specific enough to recognize later. For a one-off group outing, it helps to decide whether one person will collect everyone’s share or whether each person will pay the organizer directly. These are not special app tricks; they are practical ways to keep a convenient payment tool from creating a new round of confusion.
I would also pause before sending money to someone I do not know well. A familiar interface does not make a mistaken recipient or an unclear request harmless. Check the person and amount, and do not treat a payment note or social connection as proof that a request is legitimate. This is ordinary care for any money app, but it matters especially when a transfer is initiated quickly from a phone.
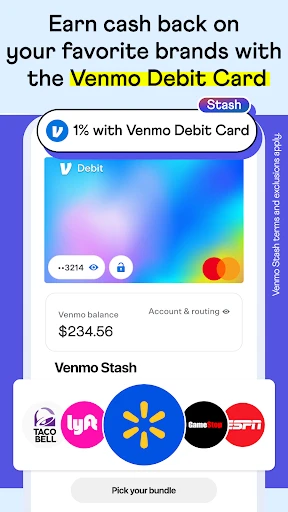
The Venmo debit card can be useful if you want to spend an existing Venmo balance without first moving it to your bank. I would see it as a convenience for that specific situation, not a reason to keep more money in the app than you need. If you normally want all your funds in your bank account, the extra card may not add much to your routine.
Speed, stability, and practical expectations
For an everyday payment, the main benefit is avoiding a separate cash handoff, not guaranteeing that every step is instant. How quickly money becomes usable elsewhere depends on the transfer choice, and a standard bank transfer can take time. I would use the app for routine settling up, not as a last-minute solution when a bill must be paid immediately from a different account.
Heavy use can make organization more important than raw speed. If you handle rent, meals, errands, and group plans in the same account, distinctive notes and a quick review of activity can help you tell payments apart. The social feed may be lively, but it is not a substitute for checking the transaction details. I would make the recipient, amount, and privacy setting part of the same quick pre-send check.
I cannot judge reliability from popularity alone, but the app’s long presence and broad adoption make it a recognizable choice for many users. No payment app removes the need to confirm a transfer or keep an eye on access to your account. If something looks wrong, stop and review the details rather than sending again in a hurry, which could create a duplicate payment.
Device fit and the final call
The listed minimum operating-system requirement is version 8.0, which gives the app a broad starting point for compatible devices. Still, a minimum requirement is not a promise that every older phone will feel equally responsive. If your device is tight on storage or already struggles with everyday apps, I would keep expectations modest and make sure the operating system and app are up to date where possible. I would not choose a phone solely around one payment app.
Overall, I recommend Venmo to people who often split ordinary expenses with friends or roommates and are comfortable managing privacy settings. I would skip it if you want a purely private transfer experience, if your contacts use a different payment method, or if you need a budgeting tool rather than a way to settle up. Its strongest quality is making familiar small payments easy to organize; its main trade-off is that social convenience asks you to pay attention to what you share and how you fund or withdraw money.
If you haven't jumped on the Venmo bandwagon yet, you might want to reconsider. I mean, who carries cash anymore, right? Venmo has become a staple in the world of digital wallets and social payment apps, and after giving it a whirl, I can see why it's all the rage.
What is Venmo Anyway?
Alright, let’s break it down. Venmo is this super handy app that lets you pay and request money from your friends. Think of it as the PayPal for millennials, but with a social twist. What sets Venmo apart is its social feed. Every payment you make or receive can be shared with a customized note, emoji, or even a GIF, making it not just a transaction but a fun interaction.
Getting Started with Venmo
Setting up Venmo is as easy as pie. Download the app, sign up using your email or Facebook, link your bank account or card, and you're ready to go. The interface is pretty intuitive; even my grandma could probably figure it out without any help. Plus, there are no fees when you pay using your bank balance or debit card. However, using a credit card incurs a 3% fee, so watch out for that if you're a credit card points fiend.
The Social Experience
One thing that stands out with Venmo is its social feature. Every time a friend pays you back for that coffee, or you split a dinner bill, you can include a quirky message or emoji. This can be a bit of a double-edged sword, though. On one hand, it's pretty entertaining to see what people write. On the other hand, do you really want everyone knowing you spent $5 on a latte? Thankfully, you can adjust privacy settings for each transaction, so you’re not broadcasting your financial habits to the world.
Security and Privacy
Speaking of privacy, Venmo does take security seriously. They use encryption to protect your card and bank details, and you can set up a PIN code for an extra layer of security. Just be sure to keep your app updated to fend off any potential security threats. Like with any app handling your money, it’s wise to stay vigilant.
Venmo in Everyday Life
I’ve found Venmo particularly useful for splitting bills, whether it’s rent with roommates or the tab at a restaurant. It beats the awkwardness of chasing people down for cash or trying to remember who owes what. Plus, you can easily transfer your Venmo balance to your bank account, although it usually takes 1-3 business days. For those in a hurry, there's an instant transfer option, but it comes with a small fee.
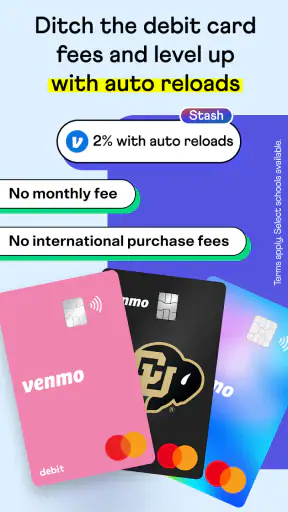
Another neat feature is the Venmo card. It’s a physical debit card linked to your Venmo balance. Super handy for when you want to spend your Venmo funds directly without transferring them to your bank first.
Final Thoughts
In a nutshell, Venmo is a must-have app in today’s digital age. It’s convenient, easy to use, and adds a dash of fun to mundane transactions. Whether you’re paying back your friend for last night's movie tickets or splitting utilities, Venmo makes it hassle-free. Just remember to keep those privacy settings in check and watch out for any fees. Happy Venmo-ing!
Venmo FAQ
What is Venmo and how does it work?
Venmo is a mobile payment service that allows users to transfer money to one another using a mobile phone app. The app connects to your bank account or credit card to facilitate transactions. It’s widely used for splitting bills, sharing rent, or making quick payments between friends, and it also offers a social aspect by letting you share payment activities on a feed.
Is Venmo safe to use for transactions?
Venmo employs encryption to protect your financial information, making transactions secure. However, it's important to use the service wisely by setting up PIN codes, enabling notifications for transactions, and ensuring you only send money to people you know. Like any digital platform, users should stay vigilant against phishing scams and unauthorized transactions.
Are there any fees associated with using Venmo?
Venmo is free to use when transferring funds from your Venmo balance, bank account, or debit card. However, there is a 3% fee for sending money using a linked credit card. Additionally, while receiving money and transferring to your bank account is free, instant transfers to your bank account incur a 1.5% fee, with a minimum fee of $0.25.
Can I use Venmo for international transactions?
Venmo currently only supports transactions within the United States. This means you can only send and receive payments from other Venmo users who have a U.S. bank account or debit card. International transactions are not supported, so if you need to send money abroad, you’ll need to use another service.
How does Venmo’s social feature work and can it be made private?
Venmo’s social feature allows users to share their payment activities on a public feed, fostering a social environment where users can like or comment on transactions. However, privacy settings can be adjusted so that transactions are private or visible to friends only, ensuring users have control over who can see their activity. Always review these settings to maintain your desired level of privacy.


