


Chime® – Fee-Free Banking
Reviews 4.7Category FinanceDownloads10.00M
Screenshots
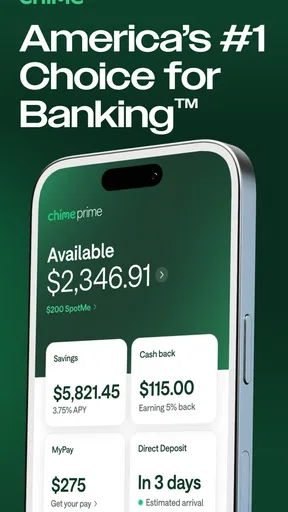
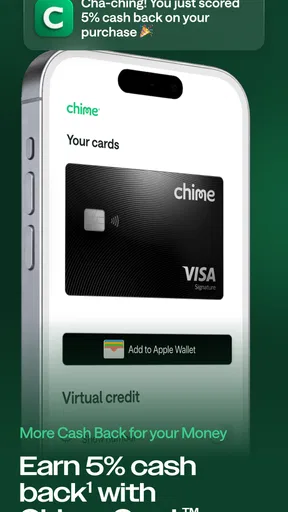
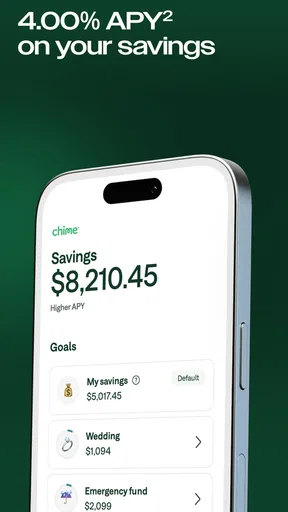
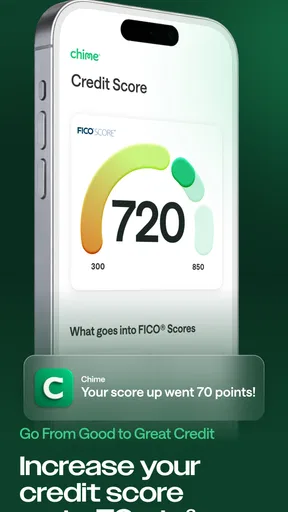
Download
Download OnGoogle PlayDownload OnApp StorePros
- No monthly fees or minimum balance requirements.
- Instant notifications for transactions.
- Fee-free overdraft up to $200.
- Access to 60
- 000+ free ATMs.
- Automatic savings features.
Cons
- No physical branches available.
- Cash deposit fees at certain locations.
- Limited customer service availability.
- No joint account options.
- Requires smartphone for full functionality.
 Analysis by Appcracy
For a household that shares bills but keeps personal money separate, a mobile bank can make everyday coordination easier without turning every purchase into a group decision. I’d treat Chime – Mobile Banking as an individual banking app first: it can suit someone who wants to manage their own spending and pay routine expenses from a phone, while a partner or housemate coordinates shared costs separately. That distinction matters. A shared device or common budget does not automatically make a bank account shared, and I would not assume the app provides family controls or joint-account tools.
Keeping shared expenses clear
Picture two housemates splitting groceries and utilities. One pays the bill, then the other sends their share through whatever payment method they already use. Chime may be useful to the person managing their own incoming money and everyday spending, but the household still needs an agreed way to track who paid what. I’d keep a simple shared note or budget outside the banking app rather than rely on one person’s transaction history to represent everyone’s finances.
This approach works best when each person has their own account access and understands which expenses are personal and which are shared. It also avoids the awkwardness of handing a banking password to someone just because you live together. If a household wants a genuinely shared account with multiple authorized users, it should compare options specifically designed for that arrangement instead of assuming an individual mobile banking app will provide it.
Setup is personal, even in a shared home
Getting started is a solo task in practical terms: the account holder enters their own details and should keep control of their sign-in. A partner can sit nearby to help compare features or talk through a budget, but I would not let another person complete identity or account steps on someone else’s behalf. Keeping setup private also makes it easier to establish who owns the account and who is responsible for its activity.
That boundary is useful for couples as well as roommates. You can coordinate recurring household costs without sharing credentials, and you can decide in advance which person pays a bill and how the other reimburses them. If someone needs another person to make transactions directly, they should check whether the account arrangement they need is supported before moving their household finances over.
Timing pay and bill payments thoughtfully
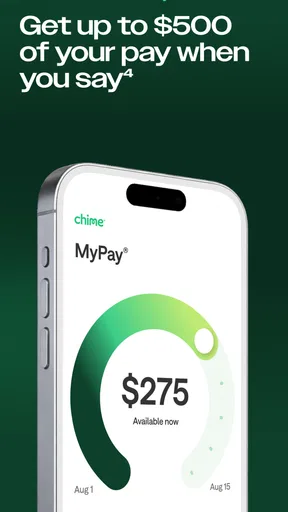
Early access to a direct deposit can help with cash-flow planning, but I would not build a household’s entire bill schedule around an assumed arrival day. A paycheck arriving earlier can create breathing room; it does not change the due date or guarantee that every deposit will appear at the same time. I’d use any early arrival as a buffer and keep enough money set aside for fixed costs before treating the balance as flexible spending.
For example, if rent and utilities come from one person’s account, they can separate those expected costs mentally—or in a budget they maintain elsewhere—before deciding what is available for groceries or discretionary purchases. The other household member can then reimburse their share on a schedule they both understand. This small routine is more dependable than checking the balance and assuming all of it is free to spend.
Worth a Read Next

MX Player Under Pressure: How Well Does It Recover When Playback Fails?

ESPN Review: A Sports App for Fans Who Follow Every Update

Zoo - Happy Animals Review: A Gentle Zoo-Building Game with a Familiar Rhythm

SoundCloud’s Community Is the Engine Behind Its Music

Harvest Right’s App Keeps You Informed, but Not Always Guided

NewsBreak Review: A Useful Local Briefing with a Crowded Feed
What the app is like in everyday use
Chime is a finance app developed by Chime, and it has a 4.7 average from around 946,000 ratings. I see that as a sign that many people find the basic mobile-banking approach useful, not proof that it will fit every household or financial routine. It is free to download, has over 10 million installs, and is rated for Everyone. The app’s current version is 5.301.0, and it runs on operating systems starting with version 10.
The everyday appeal is straightforward: check your own balance, keep an eye on money coming in, and handle routine banking from your phone rather than planning a trip around a branch visit. That can be a good fit if your needs are mostly digital and you prefer to manage your own account on your own schedule. It is less compelling if you regularly need in-person help, want a single account controlled by several household members, or rely on a specific bank service that the app does not replace.
Saving habits that work without household guesswork
Automatic round-ups can make saving feel less like a separate project, but I’d treat them as a personal habit rather than a shared household savings plan. Small amounts diverted from purchases may add up over time, yet they are not a substitute for agreeing on how much each person contributes toward a common goal. If you are saving for a shared trip or a repair, decide who owns that money and where it will be held before relying on an individual account’s savings tools.
A practical workflow is to use the app for personal cash flow, then review shared costs together at a regular time—perhaps when the rent or utility bill is due. That keeps the banking activity private while giving both people a clear view of their responsibilities. It also reduces the risk that one person mistakes another’s personal savings balance for money available to the household.
Where it differs from a traditional bank
Compared with a conventional bank app, Chime’s appeal is its phone-centered approach and emphasis on avoiding routine monthly charges, alongside early access to qualifying direct deposits. A traditional bank may be a better choice for someone who values branch assistance, wants to discuss multiple financial products face to face, or already depends on a broader set of services in one place. Neither format is automatically better; the right choice depends on what you actually use.
Compared with budgeting apps, a mobile banking app serves a different role. A budgeting tool may help a couple see spending across accounts or plan categories, while Chime is where an individual manages their banking relationship. I would not expect one app to solve both account access and household coordination. If everyone needs visibility into shared spending, choose a budgeting method that supports that goal without sharing private banking credentials.
Security and the limits of shared access
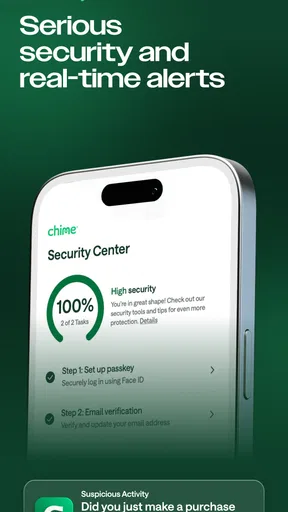
Security matters even when the household is close-knit. The original app experience includes two-factor authentication, encryption, and an option to block a card in the app if it is lost or stolen. Those protections can help an account holder manage access and respond to a misplaced card, but they do not turn a personal login into a safe shared login. I’d keep the device lock and account credentials under the account holder’s control.
On a shared phone or tablet, I would be especially careful about signing out when finished and not saving banking credentials where another user can open them casually. A household member who needs to contribute money can use a separate, agreed payment route rather than browse the account. If the device itself is used by children, an adult should decide whether banking access belongs there at all; an Everyone content rating is not a recommendation that children manage an account.
Who is likely to appreciate it—and who may not
I’d consider Chime if I wanted an individual account that is easy to check on a phone, disliked recurring monthly banking charges, and received income by direct deposit. It may also suit someone trying to build a steadier routine around everyday spending and saving. The fee-free overdraft claim is appealing, but overdraft access should not be treated as extra income or a substitute for a cushion; anyone relying on it should read the account terms and understand when it applies.
I would look elsewhere if I needed branch-based service, a clearly shared household account, or a particular set of traditional banking services that I use regularly. I’d also compare alternatives if my main goal were detailed joint budgeting rather than managing my own account. The best choice is the one that matches the actual jobs your household needs done, not simply the one with the most convenient headline feature.
Getting the most out of the routine
Before moving direct deposits or bill payments, I’d list the transactions that must keep working: rent, utilities, subscriptions, and any transfers between household members. Then I’d decide which account should handle each item and leave room for payment timing rather than changing everything at once. That makes it easier to spot a missed payment or an unexpected balance change while the new routine settles in.
I’d also agree on a simple reimbursement rule with anyone sharing expenses: what counts as a shared cost, when the other person pays their portion, and how both people will confirm it. This is not a special feature of the app; it is a practical way to avoid confusing personal transactions with household obligations. Chime can support one person’s side of that system, but the agreement itself still has to come from the people involved.
Getting Started with Chime
Signing up for Chime is as breezy as a Sunday morning. You’ll need to download the app from either the Google Play Store or the Apple App Store, and then it’s just a matter of entering some basic details. The app’s smooth interface guides you effortlessly through setting up your account. Within minutes, I was exploring what Chime had to offer.
Features That Make You Go "Wow"
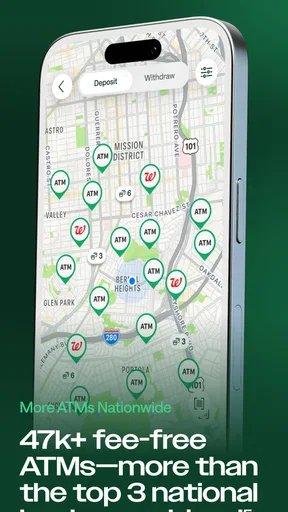
One of the first things that stood out to me was the lack of fees. That’s right, folks—no monthly fees, no minimum balance requirements, and no foreign transaction fees. It’s like a breath of fresh air in a world where banks seem to nickel and dime you at every turn. Plus, with access to over 60,000 fee-free ATMs, you’re never far from your cash.
The automatic savings feature is another highlight. By rounding up your purchases to the nearest dollar and depositing the difference into your savings account, Chime makes saving money feel less like a chore and more like a natural part of spending. I also loved the early direct deposit feature, which lets you access your paycheck up to two days early. Who doesn’t want to get paid sooner?
Security You Can Trust
When it comes to my hard-earned cash, security is non-negotiable. Thankfully, Chime gets this. The app uses robust security measures, including two-factor authentication, to keep your information safe. I found peace of mind in knowing that my data was protected by encryption and that I could instantly block my card from within the app if it was ever lost or stolen.
User Experience: Smooth Sailing
I’ve got to hand it to Chime; they’ve really nailed the user experience. The app is intuitive, with a clean design that makes navigation a breeze. Whether you’re checking your balance, transferring funds, or paying bills, everything is just a tap away. I never once felt overwhelmed or confused, which is more than I can say for some other banking apps I’ve tried.
A household-minded verdict
For a person who wants a straightforward way to manage their own money, Chime is worth considering. For a household, I’d use it as one person’s banking tool within a wider plan—not as a shared command center. That approach respects account boundaries while still making it possible to coordinate bills, reimbursements, and savings goals clearly.
Final Thoughts
To sum it all up, Chime – Mobile Banking is a solid option for anyone looking to simplify their financial life. It’s particularly great for those of us who appreciate convenience, transparency, and a no-fee approach to banking. Sure, it doesn’t have all the bells and whistles of a traditional bank, like in-branch services or loans, but what it lacks in extras, it more than makes up for in ease of use and peace of mind.
If you’re ready to ditch the fees and embrace a more seamless way to manage your money, give Chime a try. You might just find that banking doesn’t have to be a necessary evil—it can actually be a pleasant part of your everyday routine.
Chime® – Fee-Free Banking FAQ
What features does Chime – Mobile Banking offer?
Chime Mobile Banking offers a variety of features designed to help users manage their finances effectively. These include a spending account, savings account, and the ability to receive paychecks up to two days early with direct deposit. Additionally, Chime provides a fee-free overdraft service, automatic savings options, and a user-friendly mobile app interface for managing all transactions.
Is Chime – Mobile Banking safe to use?
Yes, Chime is a safe option for mobile banking. It employs advanced security measures such as two-factor authentication, encryption, and account notifications to protect user information. Chime is insured by the FDIC up to the standard maximum limit through its partner banks, ensuring that your money is protected.
Are there any fees associated with using Chime – Mobile Banking?
Chime is known for its fee-free banking services. Users can enjoy banking without monthly fees, minimum balance requirements, or overdraft fees. However, there may be fees for using out-of-network ATMs or certain other third-party fees. It's advisable to review Chime's fee schedule for detailed information.
How do I deposit money into my Chime account?
Depositing money into your Chime account is simple and convenient. Users can set up direct deposits with their employers, deposit checks via the mobile app using mobile check deposit, or transfer funds from an external bank account. Additionally, cash deposits can be made at over 90,000 retail locations nationwide.
What should I do if I encounter an issue with my Chime account?
If you experience any issues with your Chime account, customer support is readily available to assist you. Users can contact Chime support through the mobile app, by email, or via phone. Chime also offers a comprehensive help center on their website with answers to frequently asked questions and troubleshooting tips.


