

Común: Your money, your way
Reviews 4.8Category FinanceDownloads500.00K
Screenshots
Download
Download OnGoogle PlayDownload OnApp StoreDownload theAPK FilePros
- Clear overview of spending
- balances
- and recent transactions
- Useful tools for organizing money around personal financial goals
- Modern interface that is easy to navigate for most users
- Convenient access to account information from a mobile device
- Can reduce the need to visit a branch for everyday banking tasks
Cons
- Some features may depend on your country
- account type
- or bank eligibility
- Requires sharing sensitive financial information with the service
- Support options may be limited outside regular business hours
- App performance can vary after updates or on older devices
- Not all money-management features may be available on every account
 Review of Común: Your money, your way by Appcracy
When I first tried Común, I approached it with a very ordinary problem: I wanted one place for everyday money tasks rather than jumping between a transfer service, a separate card, and another app for sending funds abroad. Común is a free finance app from Comun that brings those needs together around payments, transfers to Latin America, and a Visa debit card. That combination makes it more interesting than a basic budgeting tool, but it also means the app is best judged by how smoothly a complete money journey works from start to finish.
The starting point is simple. You install it on a compatible device, create or access your account, and then decide what you actually need first. Some people will arrive because they want to pay another person. Others will be more interested in sending money to Latin America or using the Visa debit card for regular purchases. I like that these are connected use cases rather than unrelated tools, because the app feels designed around moving money through real life instead of merely displaying account information.
Comun has built an app that is clearly aimed at people who want a more direct relationship with their money. That does not mean every user will find it ideal. If you only want detailed spending charts, investment research, or a traditional bank account with a broad range of financial products, this is not the experience I would choose first. Its appeal is narrower and more practical: payments, person-to-person transfers, international sending, and card access in one mobile workflow.
Following a payment from the first tap to the final handoff
Choosing the right starting point
My first recommendation is to decide which task matters most before exploring every screen. If your immediate goal is paying someone, start there and learn the confirmation flow. If your goal is supporting family in Latin America, begin with the international transfer path and pay attention to the recipient details before you send anything. If you plan to use the Visa debit card, treat the card setup as a separate preparation step rather than assuming it is ready the moment you open the app.
This matters because financial apps can feel easy while you are browsing and become more demanding at the moment money leaves your control. I prefer to slow down at the recipient stage, check the destination carefully, and only then confirm. A useful habit is to keep the recipient's information in front of you while completing the transfer, especially when names, account details, or regional information need to match. The app can make the action convenient, but convenience should not replace a final review.
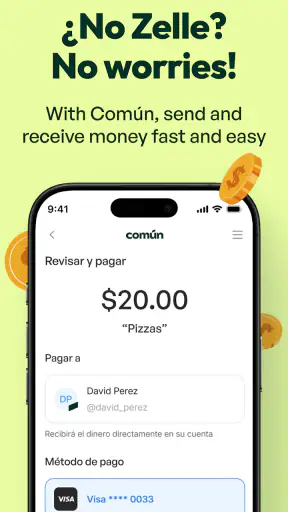
For a normal payment, the practical workflow is fairly easy to understand: choose the person, enter the amount, review the destination, and complete the handoff. The important point is that Común is not just a digital wallet sitting passively on your phone. It is meant to be used when you need to act. That makes the interface feel more purposeful than finance apps that mainly show balances and transaction history.
A realistic everyday scenario
Imagine that I need to pay a friend after we split a meal, then send money to a relative in Latin America later that week. With a conventional setup, I might use a bank app for the first payment, a specialist remittance service for the second, and a separate card app for purchases. With Común, I can begin in one finance app and keep the mental process together: identify the recipient, check the amount, confirm the transfer, and later use the international option when the purpose changes.
The benefit is not only fewer icons on my phone. It is the reduced chance of forgetting where a transaction was made. When payments, international transfers, and card spending are scattered across different services, tracking a small household budget becomes unnecessarily tiring. Keeping the actions in one place can make it easier to remember what has already been sent and which balance is available for the next task.
There is also a useful behavioral advantage here. Because the app is centered on sending and spending rather than complicated financial planning, I am less tempted to turn a simple payment into a research project. For a quick handoff, that is exactly what I want. The trade-off is that users who enjoy extensive categorization or advanced financial dashboards may find the experience less satisfying than a dedicated budgeting application.
Sending money to Latin America
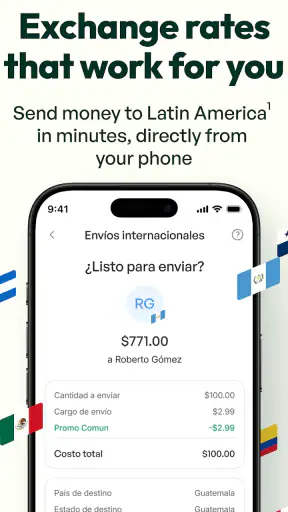
The international transfer workflow deserves more attention than a casual payment because the handoff involves another person, another location, and potentially different expectations about timing and availability. I would prepare the recipient information first, then enter the transfer inside Común, review the destination and amount, and make sure the recipient understands what to expect before I finalize the action.
That last conversation is easy to overlook. A transfer app can make the sender feel finished as soon as the confirmation appears, while the recipient may still need to check their side. In my experience, the best workflow treats the recipient as part of the process: agree on the purpose, confirm the details, and tell them when the transfer has been initiated. This is particularly important for family support, where a mistaken destination can create stress that no attractive interface can solve.
Común is especially appealing when the same person regularly sends money across borders and also needs domestic payment tools. Instead of maintaining a separate mental routine for every financial service, the user can return to one familiar app. Still, I would not use any transfer service casually just because it is convenient. Before sending a meaningful amount, I would inspect the final transaction summary and verify every detail, including the person receiving it and the amount shown at confirmation.
Another practical tip is to separate testing from important transfers. If you are new to the workflow, learn the screens with a small, low-risk payment first rather than making your first attempt during an urgent family situation. This is not a criticism of Común specifically; it is a sensible way to learn any financial app. The more important the transfer, the less room there is for discovering an unfamiliar confirmation step at the last moment.
Adding the Visa debit card to the routine
The Visa debit card changes the app from a transfer tool into something that can accompany everyday spending. I see the card as most useful for people who want their payment activity and card use to live in the same financial environment. Instead of sending money in one place and managing a separate debit card elsewhere, the Común workflow can connect those activities more naturally.
There is a small but important distinction between having access to a card and being ready to depend on it. Before making it my only payment method, I would confirm that the card has been set up correctly and that I understand how I will monitor its activity inside the app. I would also keep a backup payment option for situations where a phone, card, or account is temporarily unavailable. That is good financial hygiene, especially when an app is being used for both transfers and purchases.
For everyday spending, I would use the card where I want a straightforward debit payment and then return to the app to keep an eye on the related activity. The advantage is continuity: the card is not an isolated product but part of the same mobile money workflow. The limitation is that users looking for a broad credit-card rewards ecosystem or extensive banking services may prefer a conventional bank or a specialized card provider instead.
Understanding the handoffs between people and services
The most important part of this app is not the first tap; it is the handoff. Money may move from me to a friend, from me to a family member in Latin America, or from my account into a card purchase. Each handoff has a different risk. A local payment mainly depends on selecting the correct person and amount. An international transfer adds recipient and destination concerns. A card purchase adds the need to know whether the card is ready and whether I can access the app when I need to review activity.
I find it helpful to think of Común as a chain rather than a single button. The chain starts with my intention, continues through the details I enter, passes through confirmation, and ends when the other person or merchant can actually use the money. If one link is unclear, I should pause instead of assuming that a successful-looking screen means the whole process is complete.
This way of thinking also helps explain who will appreciate the app most. A user who frequently pays people, sends money to Latin America, and wants a Visa debit card has a reason to accept the learning curve. A user who only needs an occasional transfer may find a specialist service more familiar, particularly if that service is already trusted by the recipient. Común's value grows when several needs overlap.
What the overall result feels like
After following the workflow, my impression is that Común succeeds when I treat it as a practical money hub rather than a full replacement for every financial product. The app's focus is clear, and that focus makes common actions easier to organize. I can imagine using it for a quick payment, checking the process for a cross-border transfer, and relying on the Visa debit card for normal purchases without maintaining three separate routines.
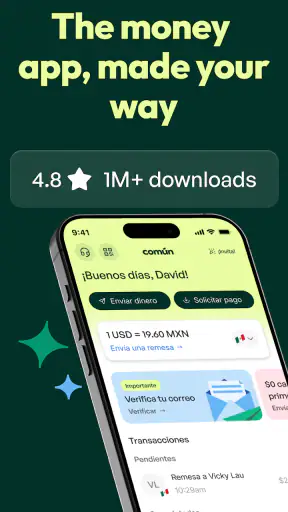
The app is also approachable for a broad audience. It is free, carries an Everyone content rating, and has reached over 500 thousand installs. Its average rating is 4.8 from around 22 thousand ratings, with roughly 2.7 thousand written reviews, which suggests that many users find the overall experience worthwhile. Those figures do not remove the need for care with financial transactions, but they do indicate that Común has attracted a substantial active audience rather than being an obscure experiment.
For someone helping relatives abroad, the strongest result is organizational. The same app can support the decision to send money and the practical action of sending it. For someone who wants a debit card alongside person-to-person payments, the result is convenience. For someone seeking a detailed financial command center, the result may feel incomplete because the app's strengths are centered on moving money, not on offering every possible way to analyze it.
Where the workflow can break down
The first weak point is the moment when a user expects convenience to eliminate verification. It cannot. A wrong recipient, an incorrect amount, or a rushed confirmation can still create a difficult situation. Común may shorten the path, but I would never treat the shorter path as permission to skip the review screen or ignore the recipient's instructions.
The second weak point is dependence on one mobile service for several tasks. Combining payments, international transfers, and a debit card is useful, but it also concentrates more of a person's routine in one app. If you prefer spreading your financial tools across providers or keeping a traditional bank as the central account, Común may work better as a companion than as your only option.
The third is the difference between a sender's experience and a recipient's experience. The person initiating a transfer may understand the app immediately, while the recipient may be expecting a different method or a different confirmation. Before using Común for a time-sensitive payment, I would make sure the recipient knows what is coming and has the information needed to recognize it. That small handoff can prevent a great deal of confusion.
There is also a fit issue for people who want advanced financial features. If your priority is investment management, complex account analysis, credit-building tools, or a large menu of traditional banking services, I would look at a full-service bank or a specialized finance app instead. Común is more convincing when the question is “How can I pay or send this money?” than when the question is “How can I manage every part of my financial life?”
Compatibility, cost, and keeping the app current
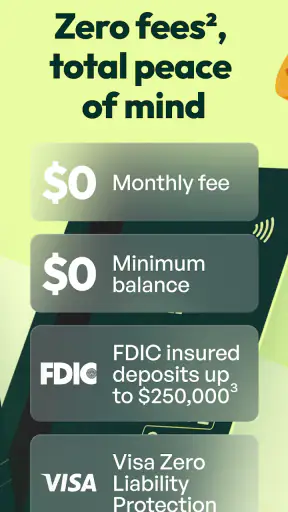
Común is free to download and use as an app, which makes trying its core workflow less intimidating than committing to a paid finance product. It was released on August 30, 2022, and the current version is 2.29.0. The listed minimum operating system is Android 10, so anyone using an older Android device should check compatibility before planning around it. The app is also available in the Android and iOS ecosystem described for this service, giving users on either major mobile platform a path to consider it.
I would still separate “free app” from “free financial activity” in my expectations. The absence of an app price does not mean every possible money movement has identical terms, timing, or conditions. Before confirming an important transaction, I would read the amount and final details presented in the app rather than relying on a general assumption that every action works the same way.
Keeping the application updated is another sensible part of the workflow. Finance apps handle sensitive actions, and an outdated version can make the experience less predictable. I would install updates before a planned international transfer or before depending on the Visa debit card during travel. This is a simple precaution, but it is more useful than discovering an interface change while standing at a checkout or trying to send urgent support.
Who should use it, and who should choose something else?
I would recommend Común to someone who wants a focused combination of person-to-person payments, transfers to Latin America, and a Visa debit card. It is particularly suitable for users whose financial life crosses between local payments and family support abroad. The unified workflow can save mental effort, and the free entry point makes it reasonable to test whether the app matches your habits.
I would be more cautious about recommending it as a sole financial home for someone who needs extensive banking services or who dislikes managing money through a phone. If you need branch access, a wide range of account types, or highly specialized financial tools, a traditional bank may be the better foundation. If you only send money internationally once in a while, compare the recipient's familiarity and the exact final terms with those of a dedicated remittance alternative before deciding.
My practical advice is to begin with a low-stakes use case, learn the payment and confirmation flow, and only then add the card or make a more important international transfer. Keep recipient details organized, check every final screen, and tell the other person what to expect. Those habits make the app's convenience work for you instead of encouraging rushed decisions.
In the end, I see Común as a focused finance app with a genuinely useful advantage: it connects several everyday money handoffs that are often split across different services. It is not a universal bank and does not need to pretend to be one. When I use it for the tasks it is built around, the path from intention to payment feels coherent. My recommendation is to try it if payments, Latin American transfers, and a debit card belong in the same routine; otherwise, a more specialized or traditional alternative may serve you better.
FAQ
What is Común: Your money, your way?
Común: Your money, your way is a personal finance app designed to help users manage everyday money in one place. Depending on your region and eligibility, it may provide tools for organizing finances, viewing transactions, making payments, or accessing other financial services. Before downloading, check the official app listing to confirm which features are currently available in your country.
Is Común: Your money, your way safe to use?
The app may use security measures such as account authentication, encrypted connections, and identity verification to help protect financial information. However, no financial service is completely risk-free. Download Común only from an official app store, use a strong and unique password, keep your device updated, and never share verification codes or login details with anyone claiming to represent the service.
Does Común charge fees for using its services?
Fees can depend on the specific feature you use, your account type, transaction method, and location. Some basic tools may be free, while transfers, card services, currency conversion, withdrawals, or other financial operations could involve charges. Review Común’s current pricing, terms, and applicable limits inside the app or on its official website before completing any transaction.
What information is required to create a Común account?
Because Común handles financial information or money-related services, registration may require personal details such as your name, email address, phone number, date of birth, and government-issued identification. The app may also request additional information for identity verification and regulatory checks. Requirements can vary by country, so make sure your details are accurate and up to date.
Can I use Común on both Android and iPhone?
Común may be available for Android and iOS, but compatibility can vary according to your device model, operating system version, and location. Check the official Google Play or Apple App Store listing before installing to confirm availability. You should also verify that your phone meets the minimum requirements and that the service operates in your country or region.


