


Intuit Credit Karma
Reviews 4.7Category FinanceDownloads50.00M
Screenshots
Download
Download OnGoogle PlayDownload OnApp StorePros
- Free credit score access.
- User-friendly interface.
- Comprehensive financial tools.
- Regular credit updates.
- Personalized financial tips.
Cons
- Limited credit bureau data.
- Ads can be intrusive.
- Privacy concerns over data.
- Not all loans available.
- Occasional app glitches.
 Analysis by Appcracy
I judge a finance app less by the first impressive screen than by whether it still helps after the novelty wears off. Intuit Credit Karma has a clear reason to return: it brings credit information and related tools together without charging to use the app. That makes it appealing for someone who wants a regular check-in, though it works best as a guide rather than a complete financial plan.
The first-week appeal: a quick way to get oriented
Credit Karma is a free finance app from Credit Karma, LLC, available on Android and iOS. Its first-week draw is easy to understand: you can get a view of your credit profile and see explanations alongside the numbers, instead of trying to make sense of a report on your own. The app has a 4.7 average from around 3.1 million ratings, and more than 50 million installs, but those figures matter less than whether its approach fits your own habits.
Getting started means creating an account and providing personal details, so this is not an anonymous calculator you can browse without setting anything up. I’d take a moment to check that you are comfortable sharing the information needed to access credit-related features before proceeding. The app is free, rated for Everyone, and its current version is 25.49; it has been available since February 28, 2013. Those basics make it easy to try, but the more useful question is what you will actually do with it after setup.
Month-to-month value: context matters more than a score
In my experience, a score is most useful when I can connect it to a real decision. Credit Karma presents scores and reports from TransUnion and Equifax, with weekly updates, and points to factors that can affect a score, such as credit utilization or a hard inquiry. That can help me notice a change and decide whether I should investigate, rather than treating a single number as a verdict on my finances.
A practical routine is to check in when something changes: after applying for credit, paying down a balance, or reviewing a report. If a score moves, I’d look at the report details and the explanation before drawing conclusions. Different lenders can use different scoring models, so a score shown in an app should be treated as a helpful reference, not a promise about what a lender will see or offer. For an important application, I would also check the lender’s own criteria.
The app also includes a credit score simulator. I find that most useful as a way to ask “what if?” and explore how a hypothetical choice might affect a score. It is not a guarantee: actual outcomes depend on a person’s broader credit file and on how events are reported. I’d use the simulator to compare scenarios and frame questions, not to make a major borrowing decision as if the result were certain.
Maintenance, trade-offs, and the point where I’d move on
Credit Karma can also surface financial products, including personalized credit card recommendations, and includes a section for taxes. That convenience comes with a trade-off: recommendations are not the same as neutral advice. Before acting, I’d compare the card’s fees, rates, rewards, and terms with alternatives from the issuer or another source. A recommendation can be a useful starting point, but it should not replace checking whether a product suits my spending and repayment habits.
Worth a Read Next
AliExpress Rewards Shoppers Who Know What They’re Looking For
Leaving Google News for X Means Trading Curation for Speed
Why PowerPoint Still Wins the Rush Before a Meeting
ReelShort Review: Bite-Size Dramas, With a Catch
My Talking Tom 2 Turns Viral Laughs Into a Daily Routine
Dream League Soccer 2026 Is Better When the Whistle Blows
For everyday maintenance, I would keep the app’s role modest: check the reports when there is a reason, follow up on unfamiliar information, and avoid turning weekly score changes into a measure of personal progress. If I only need a budget or a place to track monthly bills, a dedicated budgeting tool or a spreadsheet may be more direct. If I need help resolving a complex credit issue, I would not expect an app alone to replace tailored professional guidance.
Who will get lasting value?
I’d recommend giving it a try if you want an accessible way to review credit information, understand factors that may be influencing a score, and explore possible next steps. It is especially useful for someone who is preparing for a financial decision and wants to get organized before applying. It is less suitable if you would rather not share personal details with a finance app, want one definitive score for every lender, or are looking for a full-service budgeting system.
Security deserves a thoughtful approach whenever an app handles sensitive financial information. Credit Karma says it uses 128-bit encryption, which I find reassuring, but no security measure removes the need to protect your account and device. I would use a strong, unique password, keep my device protected, and read the app’s privacy information before connecting any financial details. That is sensible upkeep, not a reason to panic or assume the app is risk-free.
Getting Started with Credit Karma
First things first, downloading Credit Karma is a breeze. Available on both Android and iOS, it's a quick install and you're on your way. Once you open it up, you're greeted with a clean, fresh interface that just screams simplicity. Setting up an account is straightforward; just pop in a few personal details and voilà, you're ready to roll. The best part? No credit card required! It's free as a bird.
A Peek into Your Financial Health
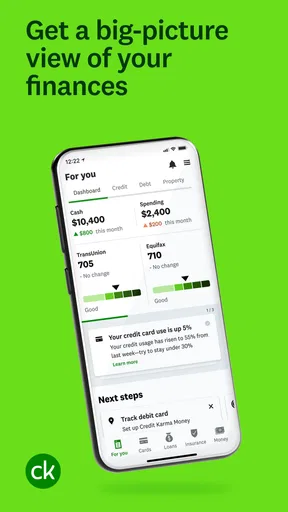
Now, let's dive into what makes this app a game-changer. Credit Karma offers you a detailed look at your credit score and report. I mean, we're talking full transparency here. You get to see your scores from both TransUnion and Equifax, which is pretty awesome since not all apps offer this dual insight. The scores update weekly, so you're always in the loop.
Besides the numbers, the app provides helpful insights into what’s affecting your score. Maybe it's the credit card utilization or a pesky hard inquiry. Whatever it is, Credit Karma breaks it down for you, and trust me, it’s like having a financial advisor in your pocket, minus the hefty fees.
Tools and Features Galore
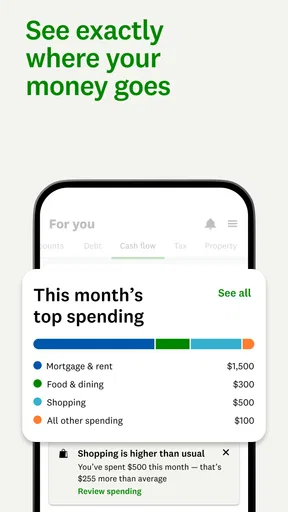
Credit Karma isn’t just about scores, though. It packs in a bunch of tools to help you manage your finances better. Need help with taxes? There’s a section for that. Looking for a new credit card? The app gives personalized recommendations based on your credit profile. I even found a great cashback card through it!
Plus, there’s a nifty credit score simulator. Ever wondered what would happen if you paid off a loan or opened a new credit line? This tool lets you play around with different scenarios, and it’s quite enlightening. And hey, knowledge is power, right?
Useful habits—and where the app can wear thin
A realistic way to use these tools is to set aside a short check-in after a major credit event rather than opening the app every day. For example, if I have just paid down a card, I can note the date, return when the information has had time to appear in the report, and compare the report details with what I expected. That is more informative than refreshing a score repeatedly, because reporting changes do not necessarily show up the moment I make a payment.
I would also keep a simple note of questions that arise while reviewing a report: an account I do not recognize, a balance that seems unexpected, or a change I cannot explain. The app can help me spot what to investigate, but the next step may involve checking with the relevant lender or credit bureau. This distinction matters: seeing an issue is useful, while resolving it may require action outside the app.
The strongest practical tip is to treat its suggestions as prompts for comparison. If a card recommendation catches my eye, I would first decide what I need—perhaps a lower ongoing cost or rewards that match purchases I already make—then compare the full terms. Chasing an offer because it appears personalized can lead me toward a product that is not right for my repayment habits. I would not open credit just to test a simulator scenario, either.
Over time, product offers can become the part that feels most tiring, especially if I opened the app mainly to check a report. I would focus on the information I came for and avoid browsing recommendations as though they were a to-do list. If the app’s product discovery is not useful to me, a bank or bureau tool with a narrower purpose may feel calmer; if I want a broader view of spending, a budgeting app is the better fit.
How it compares with other ways to check credit
Compared with checking only through a bank, Credit Karma’s appeal is having TransUnion and Equifax information together with explanations and a simulator. A bank’s own credit feature may be convenient if I already use that bank, while a bureau’s direct service may make more sense when I need to deal with a particular report. These options answer slightly different needs, so I would not assume one app replaces every source.
Compared with a spreadsheet, Credit Karma takes less manual effort for credit monitoring and presents factors in a more approachable format. A spreadsheet, on the other hand, gives me more control over a household budget, savings goals, and recurring bills. They are not competing solutions for the same job: I would use Credit Karma to understand credit information and a budget tool to plan cash flow.
Credit Karma is also not a substitute for professional advice when the situation is complicated, such as when several accounts are disputed or a major financial decision depends on details I do not understand. Its explanations can help me arrive with better questions, but a person who needs tailored guidance should seek a suitable source rather than relying on a score simulator or a product recommendation alone.
Questions I’d settle before making it a habit
Do you need to pay to use it? The app is free, and the original setup does not require a credit card. That makes it easy to try, but I would still separate “free to use” from “every recommendation is automatically right for me.” I would review each offer on its own merits and make no decision until I understand its terms.
Can its score predict what a lender will approve? I would not use it that way. The scores and reports are useful for monitoring, but lenders may use different models and consider other details. If I am preparing for an application, I would use the app to understand my profile, then check the lender’s requirements and avoid treating a displayed number as a guaranteed outcome.
How often should I check? Weekly updates make a regular glance possible, but for most people a purposeful check after a change or before a decision is more useful than daily attention. A weekly rhythm can help someone who is actively monitoring a report; it can also create needless worry if every small movement feels urgent. I would choose a cadence that informs me without taking over my attention.
What if a report looks wrong? I would note the specific account or detail, compare it with my own records, and follow up through the appropriate lender or bureau process. The app can make a discrepancy easier to notice, but I would not assume that viewing it resolves it. That is one reason I see the app as a monitoring and learning tool, not a complete dispute service.
Security and Peace of Mind
In this digital age, security is everything, and Credit Karma takes it seriously. They use 128-bit encryption to keep your data safe and sound. As someone who's a bit paranoid about online security, I found this reassuring. Plus, the app’s privacy policy is clear and straightforward—no hidden surprises.
My Final Take
So, is Credit Karma worth the download? Absolutely! Whether you’re a finance newbie or a credit score aficionado, this app offers valuable insights and tools to help you manage your financial life. It’s user-friendly, informative, and best of all, free. I’ve been using it for a while now, and honestly, it’s made keeping track of my financial health a whole lot easier. So, why not give it a whirl? You’ve got nothing to lose and a whole lot of financial clarity to gain.
Ultimately, Intuit Credit Karma doesn’t just show you the numbers; it empowers you to improve them. And in today’s world, that’s a pretty big deal.
Intuit Credit Karma FAQ
What is Intuit Credit Karma and how does it work?
Intuit Credit Karma is a personal finance app that provides free access to credit scores, reports, and insights. It works by gathering your financial information from credit bureaus and presenting it in an easy-to-understand format. The app offers personalized recommendations to help you manage your finances and improve your credit score. Users can also monitor their credit for free and receive alerts about any changes.
Is Intuit Credit Karma really free to use?
Yes, Intuit Credit Karma is completely free to use. There are no hidden charges or fees for accessing your credit score or reports. The app makes money through tailored financial product recommendations that may earn a commission if users choose to sign up. This ensures that users have access to a variety of financial tools without any cost.
How secure is my personal information on Intuit Credit Karma?
Intuit Credit Karma takes the security of your personal information very seriously. The app uses advanced encryption technologies to protect your data. Additionally, it has strict privacy policies in place to ensure your information is never sold to third parties. Users can feel confident that their sensitive financial data is secure when using the app.
Can Intuit Credit Karma help improve my credit score?
Yes, Intuit Credit Karma can help improve your credit score by providing personalized insights and recommendations based on your credit report. By understanding the factors that impact your score, such as timely payments and credit utilization, you can make informed decisions to enhance your credit standing. However, it's important to note that the app itself doesn't directly improve your score; it simply provides the tools and information needed to do so.
Does using Intuit Credit Karma affect my credit score?
No, using Intuit Credit Karma does not affect your credit score. The app performs a "soft" inquiry on your credit, which does not impact your score. Users can check their credit as often as they like without worrying about any negative effects. This feature allows for regular monitoring without the fear of harming your credit rating.


