


MyCard - Contactless Payment
Reviews 4.0Category FinanceDownloads10.00K
Screenshots
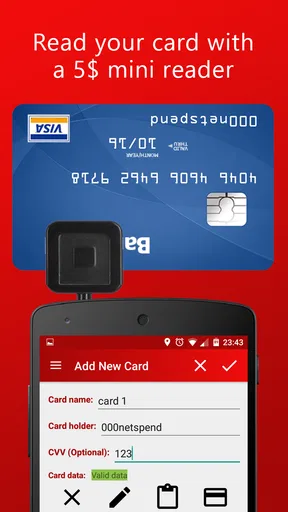
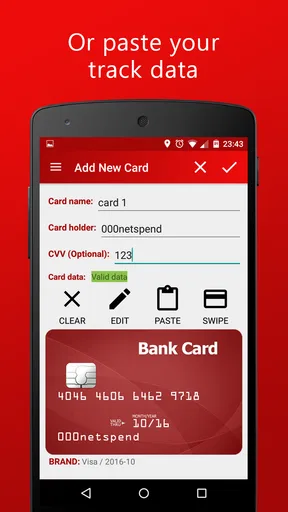
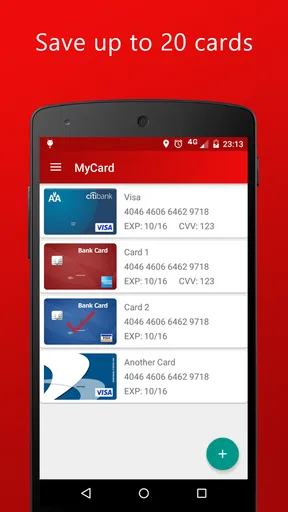
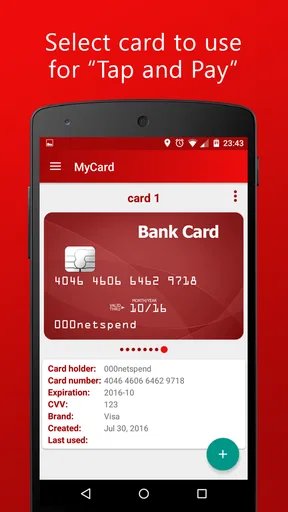
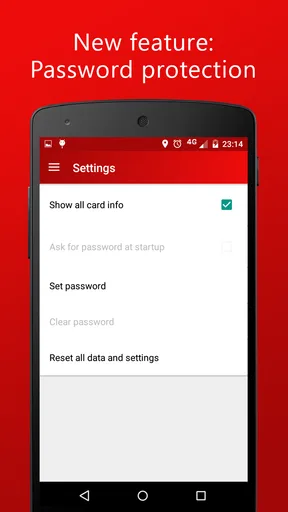
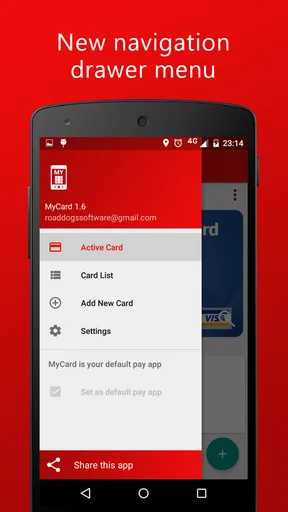
Download
Download OnGoogle PlayDownload OnApp StorePros
- Seamless contactless payments.
- User-friendly interface.
- Supports multiple currencies.
- Fast transaction processing.
- Secure encryption for data protection.
Cons
- Limited customer support.
- Requires stable internet connection.
- Not available in all regions.
- Occasional app freezes.
- No integration with all banks.
 Analysis by Appcracy
The whole appeal of MyCard - Contactless Payment rests on one simple idea: use a phone instead of reaching for a physical bank card. That can make a small moment at checkout feel less fiddly, especially when your hands are full or your wallet is buried in a bag. I like the convenience of that premise, but I’d treat it as a payment method to evaluate carefully, not as a guaranteed replacement for every card in my wallet.
What the phone-at-checkout idea changes
A phone payment is most useful when it removes a step you regularly find annoying. Rather than locating a card, taking it out, and putting it away again, you can bring your phone to the payment terminal. In a quick shop, that can mean less juggling and a smoother exit. The benefit is practical rather than dramatic: it saves a little attention at a moment when you may already be managing shopping bags, a child, or a busy queue.
That convenience also depends on the payment setup being accepted where you shop and working reliably with your bank and device. A phone-based option is not automatically more useful than a bank card simply because it is newer. Before relying on it for an entire day out, I would test it in a familiar place and keep a physical payment option available until I knew it suited my routine.
A sensible way to try it
I would begin by checking whether the app is compatible with the phone and payment arrangements I actually use, then follow its in-app setup rather than assuming every bank card can be connected. The app is called MyCard, and its developer is Road Dogs. It is a finance app with a $17.99 price, so I’d consider that cost before downloading rather than treating it like a free trial. Its age rating is Everyone, but that does not remove the need for an adult to make sensible decisions about access to payment credentials.
A low-risk first test is a familiar, modest purchase at a shop where contactless payments are already routine. Have the physical card ready, make the payment without rushing, and check that the transaction appears as expected in the account or payment records you normally use. If anything about setup, acceptance, or confirmation feels unclear, pause and resolve that before depending on the phone for a larger purchase.
Where it fits alongside ordinary cards
Compared with carrying only a bank card, using a phone can be handy when your phone is already in your hand and your wallet is not. Compared with other phone payment options, the deciding question is not which one sounds more modern; it is which one is compatible with your existing bank, device, and usual checkout terminals. I would not switch from a familiar method solely for the promise of convenience without checking those everyday details first.
There is also a useful trade-off to keep in mind: a physical card does not depend on having your phone with you, while a phone-based payment method adds another device to your checkout routine. If your phone is out of charge, unavailable, or not working as expected, the convenience disappears. Keeping a backup card is a sensible habit, especially when travelling or shopping somewhere unfamiliar.
Worth a Read Next

MX Player Under Pressure: How Well Does It Recover When Playback Fails?

ESPN Review: A Sports App for Fans Who Follow Every Update

Zoo - Happy Animals Review: A Gentle Zoo-Building Game with a Familiar Rhythm

SoundCloud’s Community Is the Engine Behind Its Music

Harvest Right’s App Keeps You Informed, but Not Always Guided

NewsBreak Review: A Useful Local Briefing with a Crowded Feed
Who is likely to appreciate it
MyCard makes the most sense for someone who already carries a compatible phone, often pays in person, and wants to try a tap-based alternative to pulling out a card. It may be less appealing if you rarely use contactless checkout, prefer not to put payment activity through a phone, or do not want to pay for an app before confirming that it fits your banking setup. Those are reasonable reasons to stick with a physical card or another option already supported by your bank.
Ever found yourself in a checkout line, fumbling through your wallet, desperately searching for that elusive card? Well, say goodbye to those days with MyCard - the contactless payment app that's changing the game!
Why MyCard?
Let's face it, we live in a fast-paced world where convenience is king. MyCard brings that convenience right to your fingertips. Imagine never having to dig through your bag again; instead, just a simple tap and you're done. It's like magic, but real!
Getting Started with Ease
Setting up MyCard is as easy as pie. Trust me, if I can do it, anyone can. Simply download the app from your app store, follow the prompts to link your bank account, and voila! You're ready to go. The interface is sleek and user-friendly, ensuring even the least tech-savvy among us can navigate it without a hitch.
Security First
Now, I know what you're thinking – "Is my money safe?" Absolutely! MyCard employs top-notch security measures to ensure your details are protected. With features like biometric authentication and real-time notifications, you can rest easy knowing your transactions are secure.
The Contactless Revolution
One of the standout features of MyCard is, of course, its contactless payment system. The joy of just tapping your phone and walking away can't be overstated. It's quick, it's efficient, and it's just plain cool. Plus, with the added bonus of reducing physical contact, it's a win-win for hygiene-conscious shoppers.
A Few Extra Perks
Beyond just payments, MyCard offers nifty features like transaction tracking and budget planning. It's like having a financial advisor right in your pocket! You can easily monitor your spending, set limits, and even get insights into your purchasing habits. It's personal finance management made simple.
In conclusion, MyCard isn't just an app – it's a lifestyle upgrade. Whether you're tech-savvy or a complete newbie, this app caters to all, making payment a breeze. So, if you haven't already jumped on the contactless bandwagon, now's the time. Trust me, once you go contactless with MyCard, you'll wonder how you ever lived without it!
How I would judge it after the first week
I would not judge a contactless payment app by one successful tap alone. I’d try it in a few ordinary settings: a quick grocery purchase, a café stop, and a shop where I normally pay with a card. That gives a better sense of whether the phone is genuinely convenient in my routine, rather than merely novel on the first use. I would also check that I can recognize each payment afterward, since a fast checkout is less helpful if I cannot confidently match a purchase to my spending.
A small practical tip is to decide in advance where the phone will be while you approach the terminal. If it is buried in a bag, the app may not save any effort; if it is already in your hand for a shopping list or travel information, the tap can feel natural. I’d keep the wallet accessible during early tests, too. That way, a declined or unrecognized payment does not leave me holding up a queue while I troubleshoot.
Questions worth settling before depending on it
Will it work with your particular bank and device? That is the first thing I would establish in the app’s setup flow, because compatibility is the difference between a useful daily shortcut and an install that never becomes part of your routine. Does every shop accept it? I would not assume so; the practical test is whether the terminal and payment arrangement support the transaction. Can it replace your wallet completely? I would say no—not until you have tested it and still have a backup for situations when your phone is unavailable.
It is also worth asking whether the purchase price makes sense for how often you pay in person. The listed price is $17.99, which makes the decision more deliberate than trying a no-cost utility. If you expect to use it regularly and value having a phone-based option, that cost may feel worthwhile. If you mainly shop online or already find your card quick and dependable, the added convenience may not justify paying for another way to complete the same purchase.
What to verify before making it your default
My practical recommendation is to confirm the setup details, test a small transaction, and learn how you will review payment activity before making MyCard your first choice at the register. Its current version is 1.21, and the app first appeared on March 22, 2016; it has a 4.0 average from about 285 ratings, with over 10,000 installs. Those figures give a basic sense of its presence, but they cannot tell me whether it will suit a particular bank or phone, so I would let a real test decide that.
The best everyday scenario is a quick stop when your phone is already with you: picking up a drink on the way to work, for example, without unpacking a bag to find a card. The weaker scenario is a long outing where the phone is also needed for navigation and communication, or a place where you are uncertain about payment acceptance. In that case, a physical card remains the simpler fallback, and carrying both avoids turning a minor convenience into a source of stress.
My final take on the trade-off
For me, the appeal is narrowly defined and useful: a phone can make an in-person payment easier when the setup works and the device is ready. I would not mistake that convenience for a reason to abandon ordinary payment options, nor would I assume that an app’s security claims answer every personal concern. I’d make the choice based on compatibility, comfort with phone payments, and whether I will use the feature often enough to value the cost.
The original pitch is appealing, but I would be cautious about treating extra functions or security details as a substitute for checking how the app behaves on my own device. MyCard is best approached as an option to test in a controlled, everyday way. If that first small purchase is straightforward and the follow-up record makes sense, it may earn a place in your payment routine; if not, your usual card remains a perfectly sensible choice.
MyCard - Contactless Payment FAQ
What is MyCard and how does it work?
MyCard is a cutting-edge contactless payment app that allows users to make secure transactions using their smartphones. By linking your bank account or credit card, you can tap your phone on compatible payment terminals to pay for goods and services. The app uses NFC (Near Field Communication) technology, ensuring quick and seamless payment experiences.
Is MyCard secure for online transactions?
Yes, MyCard is designed with top-notch security features to protect your financial information. It incorporates advanced encryption and tokenization technologies, ensuring that your card details are never shared with merchants. Additionally, it offers biometric authentication options like fingerprint or facial recognition, adding an extra layer of security to your transactions.
Can I use MyCard internationally?
MyCard supports international payments, making it a convenient choice for travelers. However, availability might depend on the country and the participating merchants. It's advisable to check with your bank or MyCard's customer support to confirm international usage and any associated fees before traveling.
What are the device requirements for using MyCard?
To use MyCard, you need a smartphone with NFC capabilities running on Android or iOS. Ensure your device's operating system is updated to the latest version for optimal performance. Additionally, your phone must have a secure lock screen enabled, such as a PIN, pattern, or biometric lock, to use the app.
Are there any fees associated with using MyCard?
MyCard itself doesn't charge users for making transactions; however, fees might be applied by your bank or card issuer. These could include foreign transaction fees when used internationally or charges for exceeding transaction limits. It's best to consult your bank's fee schedule or MyCard's terms of service for detailed information.


