


MyMoney Pro - Expense & Budget
Reviews 4.7Category FinanceDownloads10.00K
Screenshots
Download
Download OnGoogle PlayDownload OnApp StorePros
- User-friendly interface
- Comprehensive financial tracking
- Customizable budget categories
- Secure data encryption
- Multi-currency support
Cons
- Limited free version features
- Occasional sync issues
- No investment tracking
- Ads in free version
- No dark mode available
 Analysis by Appcracy
I usually start looking for a money manager when I can see my bank balance but still can’t explain where the month’s money went. That is the gap MyMoney Pro - Expense & Budget is meant to help with: turning day-to-day transactions into a clearer picture of spending and savings. It is a paid finance app by Ananta Raha, and I’d think of it as a hands-on tracker rather than a magic fix. Its value depends on whether you’re willing to enter information consistently and then use what the summaries show.
That distinction matters before you begin. Many banking apps automatically display transactions, which is convenient, but their categories and views may not match the way you want to plan. A manual money manager asks for more attention in return for more deliberate record-keeping. If you like knowing exactly why a purchase belongs in a category, that trade can be worthwhile. If you want every transaction pulled in without effort, this style of app may feel like another chore.
Start with a simple picture of your money
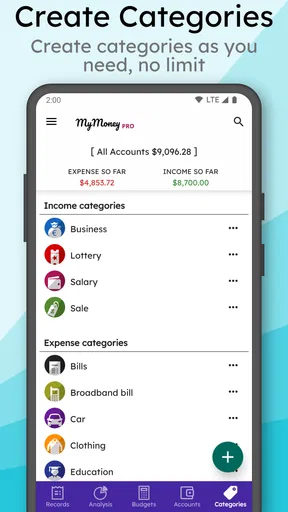
I’d begin with only the basics: the income you want to track, the expenses that recur, and a few categories that reflect your real habits. It can be tempting to create a category for every tiny distinction, but too much setup makes logging slower. Groceries, transport, household bills, eating out, and personal spending are often enough to reveal useful patterns at first. You can always make the system more detailed once you know what questions you want it to answer.
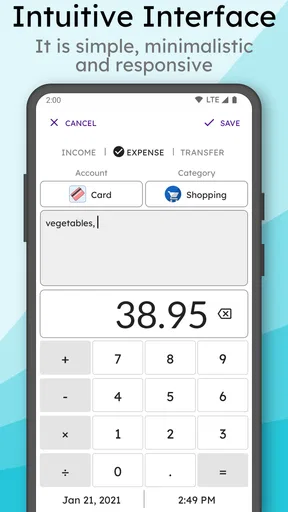
First off, setting up MyMoney Pro is as breezy as a Sunday morning. The interface is super intuitive, so even if you’re not a tech whiz, you’ll find your way around pretty easily. You start by entering your income sources and expenses, and voila, you’re on your way to tracking your finances like a pro.
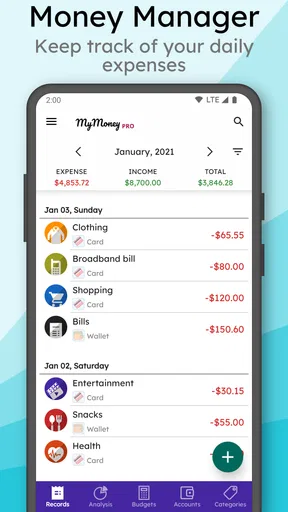
For a realistic first week, I’d record purchases when I make them or at a predictable time each evening. A quick note after lunch is more reliable than trying to reconstruct a week of small card payments from memory. Cash spending deserves special attention: it is easy to forget a coffee or a market purchase once the receipt is gone. The habit is more important than perfect detail on day one; a steady record gives the budget something useful to work with.
From daily entries to a usable plan
One practical choice is to separate fixed commitments from flexible spending. Rent or a regular bill behaves differently from takeout, so combining them into one broad “expenses” bucket can hide the decisions you actually control. I’d enter recurring costs early, then set category budgets around the remaining money. That makes the limits more realistic than choosing round numbers without first accounting for essentials.
Features that Stand Out
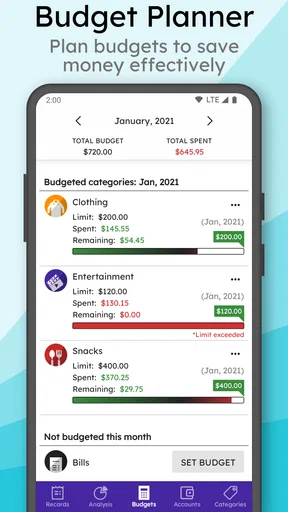
One of the coolest features is the budgeting tool. It’s like having a strict yet caring parent who keeps you in check. You can set up budgets for different categories like groceries, dining out, and leisure. The app sends you alerts when you’re nearing your limit, which is both a blessing and a curse, because, who doesn’t love a little splurge now and then?
Worth a Read Next

AliExpress Rewards Shoppers Who Know What They’re Looking For

Leaving Google News for X Means Trading Curation for Speed

Why PowerPoint Still Wins the Rush Before a Meeting

ReelShort Review: Bite-Size Dramas, With a Catch

My Talking Tom 2 Turns Viral Laughs Into a Daily Routine

Dream League Soccer 2026 Is Better When the Whistle Blows
In practice, I’d treat an alert as a prompt to review, not as a command to stop spending. If the groceries category is close to its limit halfway through the month, check whether a large planned shop is still ahead before changing the budget. If dining out is already tight, the reminder can help you choose a lower-cost meal before the expense happens. This is one of the useful trade-offs of category budgeting: it makes a broad goal concrete, but a rigid limit can mislead if spending is uneven across the month.
A small workflow improvement is to keep category names stable. If the same kind of purchase moves between “food,” “groceries,” and “household” from week to week, the report becomes harder to interpret. I’d decide where mixed purchases belong and use that rule consistently. For a supermarket receipt that includes toiletries, for example, choose whether you’ll record the whole trip as groceries or split it only when the distinction matters to your decisions. The point is not accounting perfection; it is making comparisons meaningful.
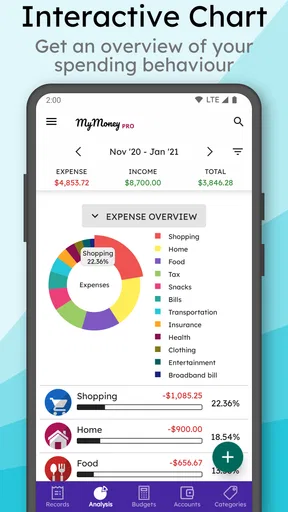
Another awesome feature is the detailed reports it generates. Ever wondered how much you spent on coffee last month? Well, MyMoney Pro has got you covered. The reports are visually appealing and easy to understand, making it simple to see where you might need to cut back or where you can afford to spend a little more.
Make the reports answer a real question
I get more out of a report when I open it with a specific question: did weekday lunches rise, are household costs crowding out savings, or is a particular category consistently underestimated? Looking at every chart without a decision in mind can turn money tracking into passive browsing. A useful routine is to compare the report with the budget, pick one adjustment, and leave the rest alone until the next review. That keeps the app from encouraging a dramatic overhaul based on a single unusual week.
Reports are also a handoff point between recording and planning. A total is only useful if it changes what I do next: perhaps I lower a leisure budget that has never been realistic, or reserve more for a predictable bill. If a category spikes because of a one-off purchase, I would not automatically treat that as a new monthly pattern. Keeping that distinction in mind is a simple way to avoid overcorrecting after an unusual expense.
For saving toward something specific, I’d use the spending picture to find an amount that can be set aside without relying on an optimistic guess. A weekend trip, replacement appliance, or annual payment becomes easier to plan for when I first see what flexible spending is doing. The app can support that decision through tracking and budgeting, but the useful result still comes from choosing a sustainable target and revisiting it when circumstances change.
Where it fits among money tools
Compared with a bank’s built-in spending view, a dedicated tracker can be more intentional: you decide what counts as groceries, leisure, or another category, instead of accepting whatever grouping your bank displays. The downside is the extra input. Compared with a spreadsheet, the app offers a purpose-built interface and reports, while a spreadsheet gives a confident user more freedom to invent formulas and layouts. I’d choose this app if I want structured tracking without designing my own system; I’d choose a spreadsheet if I enjoy customizing every detail.
It is also different from a simple notes app or a list of monthly bills. Those can record isolated facts, but they do not provide the same budgeting-and-reporting workflow described here. On the other hand, someone who only needs to remember a handful of due dates may not need a full finance tracker at all. The best choice depends on whether I want to understand patterns in spending, not merely keep a reminder list.
The app has a 4.7 average from around 5.6 thousand ratings, and it has passed 10 thousand installs. Those figures suggest that plenty of people have tried it, but I’d still judge the fit by the routine it asks of me. It costs $4.99, so I’d want to be confident that I’ll keep recording transactions rather than paying for a tool that I abandon after a few days. It is rated for Everyone, runs on Android 5.0 or later, and version 5.8-pro is the current release. The app first appeared on November 10, 2019.
Syncing and Security
For those of us who are always on the go, the app syncs seamlessly across multiple devices. So whether you’re on your phone, tablet, or laptop, your financial data is always at your fingertips. Plus, the security features are top-notch. With encryption and biometric login options, you can rest easy knowing your financial info is safe and sound.
Having information available on more than one device can help when the person who makes a purchase is not the person who later checks the budget. Still, syncing is a handoff, not a substitute for agreeing on a shared routine. If two people record the same purchase, or use different categories for similar expenses, their picture can become confusing. I’d settle on who logs which transactions and how shared costs are categorized before relying on the combined view.
Because money records are personal, I would also make a practical habit of protecting access to the device and using the available sign-in safeguards. Encryption and biometric login are reassuring features, but they do not remove the need to keep a phone secure or to think carefully about who can unlock it. I would not use a finance tracker as a place to store sensitive details that are not needed for budgeting.
Who will get the most from it
I think this is best for someone who wants a clearer month-to-month view and is willing to make manual tracking part of a routine. It can suit a person trying to rein in frequent small purchases, a couple looking for a shared view of household categories, or someone building a more realistic spending plan before saving for a goal. In each case, the benefit comes from returning to the records and making a small decision, not from installing the app alone.
It is less suitable for someone who expects automatic bank feeds, hands-off categorization, or a full financial dashboard without regular input. It may also be the wrong tool if money tracking makes you anxious or if a strict budget prompts unhelpful guilt over ordinary spending. I’d keep categories broad, check them at a calm time, and treat the numbers as information rather than a verdict. If you need detailed tax accounting or business bookkeeping, a personal expense tracker is not a replacement for a tool built for those jobs.
One question I would ask before paying is whether I’m comfortable entering transactions myself. The app’s workflow is most useful when the records are current; if I routinely put off logging purchases, the reports can look tidy while missing the small expenses that matter. Another is whether I need a single-device habit or a shared one. Syncing can make access easier, but people sharing a budget should decide how they will avoid duplicate entries and keep categories consistent.
I’d also think about what I want the first review to accomplish. “Spend less” is too vague to guide a category budget. “Find room for a monthly savings contribution without changing essential bills” is more actionable. After a few weeks of entries, I can look for a flexible category that is higher than expected, choose one adjustment, and see whether it holds. That approach gives the app a fair trial without pretending a short snapshot defines my finances forever.
What could interrupt the routine
Now, no app is perfect, and MyMoney Pro does have its quirks. Some users have mentioned that the app can be a bit slow to load at times, especially if you have tons of data stored. A few tweaks here and there, and it would be running like a well-oiled machine.
That kind of slowdown matters most when I am trying to record a purchase quickly. If a logging session feels cumbersome, I’m more likely to postpone it, and postponed entries are harder to remember accurately. A practical workaround is to keep the routine short: enter the amount and the category while the purchase is fresh, then save deeper report reviews for a quieter moment. I would also avoid making the category system so elaborate that every transaction becomes a decision.
Another minor hiccup is the price. While it’s not exorbitant, it’s not exactly cheap either. That being said, if you’re serious about getting your finances in order, it’s a worthwhile investment.
For me, the price is easiest to justify when I have a clear use for both tracking and budgeting, rather than wanting a generic finance app to try out. If I only need an occasional spending total, a basic bank view or a simple spreadsheet may be enough. If I want a repeatable routine that links entries to category limits and readable reports, paying for a dedicated tool makes more sense—provided I actually use it.
The month-end result
At the end of a typical month, I would not expect a perfect forecast or a sudden transformation. The worthwhile outcome is more modest: I can see which categories absorbed the money, identify one adjustment for next month, and decide whether my savings plan fits the way I really spend. That is a useful result because it turns vague worry into a specific next step.
MyMoney Pro is strongest when I treat it as a steady record rather than a strict judge. Start with a few categories, enter purchases consistently, review the budget alerts in context, and use reports to make one sensible change at a time. If that sounds like a routine you can keep, it offers a focused way to understand personal spending. If you need automatic transaction collection or advanced accounting, I’d look elsewhere; for a person who wants hands-on control, it can make everyday money decisions easier to see.
So, if you’re ready to take control of your financial life, give MyMoney Pro a whirl. It’s got the tools you need to track your spending, set budgets, and even save a little for that dream vacation. And hey, you might just find that managing your money is kind of fun. Who knew?
MyMoney Pro - Expense & Budget FAQ
What features does MyMoney Pro - Expense & Budget offer?
MyMoney Pro - Expense & Budget provides a comprehensive suite of financial management tools. It includes budget tracking, expense categorization, financial goal setting, and real-time expenditure analysis. The app offers personalized insights and reports to help users manage their finances effectively. It also supports multi-currency transactions and cloud synchronization for data backup.
Is MyMoney Pro - Expense & Budget available for both Android and iOS devices?
Yes, MyMoney Pro - Expense & Budget is available for download on both Android and iOS platforms. Users can find the app on Google Play Store for Android devices and the Apple App Store for iOS devices. This cross-platform availability ensures that users can manage their finances seamlessly across different devices.
Does MyMoney Pro - Expense & Budget require any in-app purchases?
While MyMoney Pro - Expense & Budget offers a robust free version, it also includes optional in-app purchases. These purchases unlock premium features such as advanced analytics, additional reporting tools, and customization options. Users can choose to upgrade based on their personal or business financial management needs.
How does MyMoney Pro - Expense & Budget ensure data security?
MyMoney Pro - Expense & Budget prioritizes user data security by employing advanced encryption technology to protect sensitive information. Additionally, the app offers secure cloud synchronization, ensuring that user data is safely backed up and accessible only to authorized devices. Users can also enable biometric authentication for an added layer of security.
Can I use MyMoney Pro - Expense & Budget to track expenses in multiple currencies?
Yes, MyMoney Pro - Expense & Budget supports multi-currency transactions, making it ideal for users who deal with international finances. The app allows users to set default currencies for accounts and automatically converts foreign transactions to the chosen currency using real-time exchange rates. This feature is essential for travelers and international business professionals.


