


Skrill - Fast, secure payments
Reviews 4.5Category FinanceDownloads10.00M
Screenshots
Download
Download OnGoogle PlayDownload OnApp StorePros
- Fast transactions with low fees.
- Wide global payment network.
- Supports multiple currencies.
- User-friendly interface.
- Secure with two-factor authentication.
Cons
- Limited customer support options.
- High fees for currency conversion.
- Account verification can be slow.
- Not accepted by all merchants.
- Occasional app stability issues.
 Analysis by Appcracy
I tend to judge a money app by what happens when a transfer is time-sensitive: can I find the right action quickly, understand what I’m about to do, and check the result afterward? Skrill is built around sending and receiving money from a phone, and that direct purpose makes it easier to approach than a broad banking app with many unrelated tools. I’d consider it when I need a dedicated digital payment account, while keeping in mind that a quick-to-use interface does not, by itself, guarantee that every transfer will arrive instantly.
What “fast” means in everyday use
The app’s strongest speed advantage is the short path from opening it to handling a payment. The original experience I describe below is centered on an intuitive process and a clear dashboard, which matters when I’m trying to make a straightforward transfer rather than learn a complicated financial system. Still, I separate fast navigation from payment delivery: the first is something an app can make feel simple, while the timing of a transfer can depend on the circumstances of the transaction.
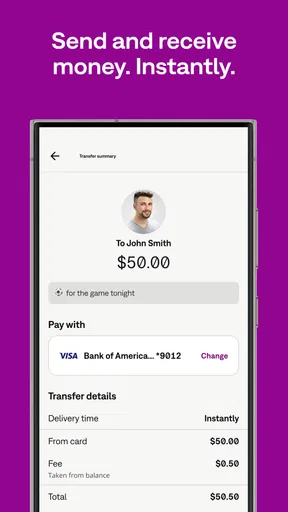
For a practical example, imagine a friend has paid for a shared meal and I want to send my part while we are still together. A phone-based payment app can make that handoff feel more convenient than asking for bank details or putting it off until later. I would check the recipient carefully, review the amount and any displayed details, and only then confirm. That small pause is useful: speed is helpful, but correcting a payment sent to the wrong person is not a good trade for saving a few seconds.
When use gets heavier
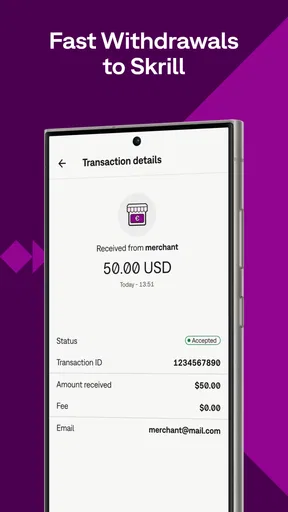
A simple transfer is only one kind of use. If I were receiving payments for freelance work, keeping money in a digital account, and making occasional international payments, I’d want to treat the balance as part of a routine rather than assume the app replaces every financial tool I use. The account view and transaction tracking described in the original review can help me check what has happened, but I would still keep my own records for work income, shared expenses, or tax preparation. A payment history is useful evidence for my own bookkeeping; it is not a substitute for organizing those records in a way that suits my needs.
One practical habit is to check the transaction details immediately after a payment instead of relying on memory at the end of the week. I can confirm that the amount and recipient look right while the context is fresh, then make a note of the purpose if I need it later. This is especially useful when several payments have similar amounts. It also helps me notice a mismatch early, rather than discovering it while trying to reconcile a busy month.
For people who make frequent payments, the convenience of a dedicated account may be worth having alongside a bank account. But I would avoid moving more money into any payment service than I expect to use until I understand how it fits my own habits. A separate balance can make everyday spending easier to track, yet it also means I have another account to monitor and secure.
Reliability is more than a smooth screen
A clean dashboard can make routine tasks feel dependable, but I judge reliability by the whole sequence: I need to reach the account, identify the intended action, review the details, and later understand the transaction record. Skrill’s straightforward layout is a strength in that sequence. Its usefulness, however, depends on being able to access the account when needed and on the payment working for the particular recipient and situation. I would not promise myself that every transfer will be immediate just because the app is designed for convenient payments.
Worth a Read Next

MX Player Under Pressure: How Well Does It Recover When Playback Fails?

ESPN Review: A Sports App for Fans Who Follow Every Update

Zoo - Happy Animals Review: A Gentle Zoo-Building Game with a Familiar Rhythm

SoundCloud’s Community Is the Engine Behind Its Music

Harvest Right’s App Keeps You Informed, but Not Always Guided

NewsBreak Review: A Useful Local Briefing with a Crowded Feed
If a payment appears to take longer than I expected, the sensible first step is to look at its status and details in the app rather than immediately submit the same payment again. Sending a duplicate can create a more difficult problem than waiting to understand what happened. I’d also make sure I’m using the account information associated with the correct recipient, especially when paying someone I have not dealt with before. These are ordinary precautions, but they matter more than tapping quickly.
Account protection deserves the same practical approach. The original review describes encryption and two-factor authentication as part of Skrill’s security setup, and I see those as reasons to take login protection seriously, not as a reason to become careless. I would use a strong, unique password, keep access to my verification method, and avoid approving a prompt I did not initiate. If I change phones or lose access to a verification method, I’d use the account’s recovery process rather than repeatedly guessing credentials or sharing security details with someone claiming to help.
Device demands and day-to-day fit
Skrill is a finance app from Paysafe Holdings UK Limited, and it is free to install. It has been available since September 1, 2014, and the current version is 3.174.0-2025112415; the stated minimum operating-system requirement is 7.0. Those details make it possible to check basic compatibility before installing, but they don’t tell me how the app will feel on every individual phone. Available storage, the device’s general condition, and a working connection can all affect the experience of using a financial app.
I would keep the app updated through the usual app-store route and make sure the phone itself has a screen lock. That is a simple way to reduce the chance that someone who picks up an unlocked device can casually open a money account. I’d also avoid relying on a payment app as my only way to access funds when I know I may be without a dependable connection or phone battery. A phone-first workflow is convenient, but it makes the phone part of the payment routine.
Resource use is difficult to judge from the app’s purpose alone, so I wouldn’t assume it is unusually light or demanding. For most people, the more relevant test is whether it opens reliably on their own device and whether the payment steps remain clear during ordinary use. If an older phone struggles with several apps running, closing what I’m not using before a time-sensitive task is a reasonable general habit, not a guarantee that any one payment will process faster.
Who benefits most—and who may prefer something else
I see Skrill as a better fit for someone who regularly needs a phone-based way to send or receive money, including people who deal with international payments and want a digital balance they can manage separately. The app has an average rating of 4.6 from around 228,000 ratings, with more than 3,000 written reviews and over 10 million installs. That broad use suggests it is familiar to many people, but popularity alone cannot establish whether it suits my particular recipient, payment route, or priorities.
Compared with a bank’s own transfer tools, a dedicated payment app can feel more focused and convenient for online transactions. A bank may be the better choice when I want payments and account balances kept together, or when a particular recipient is easiest to pay through a bank transfer. Compared with cash, Skrill avoids the need to meet with someone just to hand over money, but it depends on both sides being able to use a digital payment method. There is no universal winner: I’d choose based on who I’m paying and how I need the money handled.
I would skip it if I only make rare payments and already have a method that works well, because another financial account can mean another login and another balance to keep track of. It may also be the wrong tool if I need a payment method that a particular merchant or recipient does not accept. Before relying on it for an important transaction, I’d check the recipient’s preferred method and review the payment details shown in the app. That is more useful than assuming that a service suited to one transfer will suit every payment.
Seamless Transactions
When it comes to online payments, we all value speed and security. Skrill hits the nail right on the head. Whether you're transferring funds to a friend, family member, or even paying for services, the process is incredibly intuitive. All you need is the recipient's email address, and you're good to go. No fuss, no muss!
User-Friendly Interface
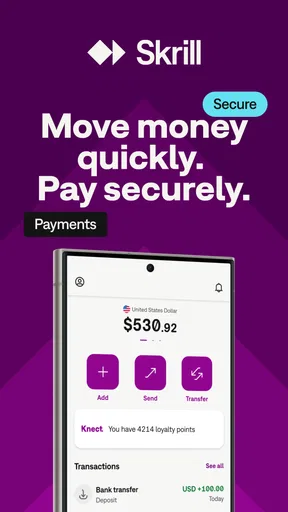
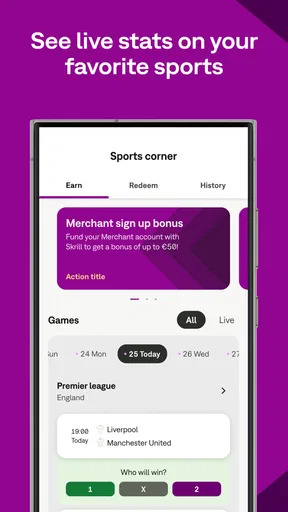
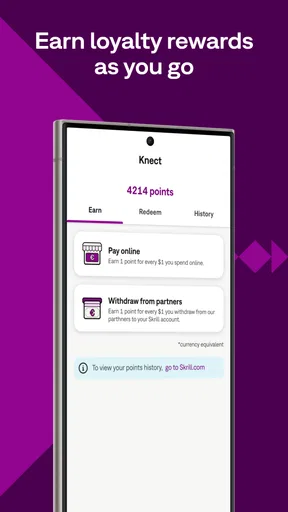
One thing I absolutely love about this app is its user-friendly interface. It's designed in such a way that even if you're not tech-savvy, you'll find your way around without a hitch. The dashboard is clean, and everything is laid out in a manner that doesn’t overwhelm you with information. You can easily track your transactions, view your balance, and manage your account settings with just a few taps.
Security at Its Best
In today’s digital age, security is paramount. Skrill takes this seriously. With advanced encryption techniques and two-factor authentication, your funds and personal details are always protected. I never felt uneasy using the app, knowing that they prioritize my financial safety.
International Transfers Made Easy
If you frequently deal with international transactions, this app is a lifesaver. It supports multiple currencies, making it convenient to send and receive payments globally. Plus, the exchange rates are quite competitive, which is a big plus if you’re handling significant amounts of money.
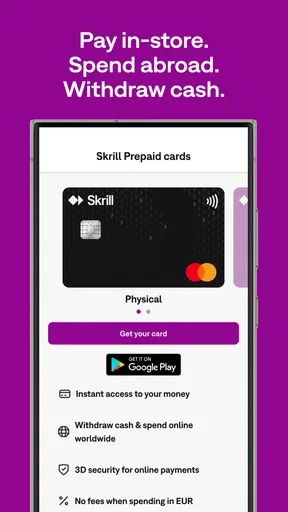
Another feature worth mentioning is their prepaid card. It allows you to use your Skrill balance for everyday purchases, just like any other debit or credit card. It’s a handy addition if you prefer cashless transactions.
Conclusion: A Reliable Payment Solution
All in all, Skrill is a reliable and efficient payment solution that I’d recommend to anyone looking for a fast and secure way to handle their online transactions. Whether you’re a business owner, a freelancer, or just someone who frequently sends money online, this app has got you covered. With its ease of use, top-notch security, and international capabilities, it’s an app that truly stands out in the crowded world of digital payments.
My overall view is positive, with one important qualification: I’d use Skrill for the kinds of payments its focused design makes convenient, while keeping a bank account or another suitable option available for situations it does not fit. The app is free, and its age rating is Everyone, so it is accessible to a broad audience; that does not remove the need to manage an account carefully or check that a payment is right for the person and purpose. If you value a clear mobile payment routine and have recipients who can use it, it is worth considering. If your needs are occasional or your usual payment method already works, there is no need to add another account just for the sake of having one.
Skrill - Fast, secure payments FAQ
What is Skrill and how does it work?
Skrill is a digital wallet and payment platform that allows users to make secure, fast, and convenient transactions online. It supports various payment methods, including credit cards, bank transfers, and cryptocurrencies. Users can send and receive money, make online purchases, and store funds within their Skrill account, providing a versatile solution for personal and business financial needs globally.
Is Skrill safe to use for online transactions?
Yes, Skrill is considered safe for online transactions as it uses advanced security measures, including two-factor authentication and encryption technologies, to protect user data and financial information. Additionally, it is regulated by financial authorities, ensuring compliance with industry standards. However, users should always be cautious and follow best practices for online security to protect their accounts.
Are there any fees associated with using Skrill?
Skrill charges various fees depending on the type of transaction. For example, there might be fees for sending money, receiving funds, currency conversion, and withdrawals. It's important for users to review the fee structure on Skrill's official website to understand the costs involved. While some transactions may be free, others can incur charges, so being informed is crucial.
Can I use Skrill for international transactions?
Yes, Skrill supports international transactions, allowing users to send and receive money globally. It supports multiple currencies and provides competitive exchange rates, making it a convenient choice for cross-border transactions. However, users should be aware of any applicable fees for currency conversion and international transfers, which can vary depending on the countries involved.
What platforms support the Skrill app?
The Skrill app is available on both Android and iOS platforms, making it accessible to a wide range of smartphone users. It can be downloaded from the Google Play Store for Android devices and the Apple App Store for iOS devices. This accessibility ensures that users can manage their accounts and perform transactions on the go, with a user-friendly interface across both platforms.


